• Home
  • About Mark Skousen
    • Catalog
    • Mark Skousen Biography
    • Commonly Asked Questions
    • Jo Ann Skousen Biography
    • Mark Skousen’s Family and Famous Relatives
    • Books Recommended by Mark Skousen
    • Personal and Miscellaneous
  • Books
    • Economics Books
      • EconoPower: How a New Generation of Economists Is Transforming the World
      • The Big Three in Economics: Adam Smith, Karl Marx and John Maynard Keynes
      • The Making of Modern Economics
      • The Structure of Production
      • Vienna & Chicago, Friends or Foes?
    • Finance and Investing Books
      • Maxims of Wall Street
      • A Viennese Waltz Down Wall Street: Austrian Economics for Investors
      • Investing In One Lesson
      • High Finance on a Low Budget
      • The New Scrooge Investing
  • Interviews
  • Appearances
  • Online Press Kit
    • Contact Information
    • Biographical Information
    • Headshots
    • List of Current Books
    • Forecasts & Strategies, Trading Services and Weekly Blog
  • FreedomFest
  • Persuasion vs. Force

MSKOUSEN.COM

Mark Skousen's Personal Website for the Best of Money & Economics

  • News
  • Economics
  • Personal Finance
  • Investing & Markets
  • Forecasts & Strategies
  • Politics & Liberty
You are here: Home / Archives for Ned Piplovic

My Schedule at FreedomFest 2026 – Exciting Topics at this Year’s FreedomFest

July 3, 2026 By Ned Piplovic Leave a Comment

Dear FreedomFesters,

Greetings and happy July 4th! 

To get you in the mood for FreedomFest, this Sunday, July 5th, I’ll be appearing as Ben Franklin along with David Shippey appearing as George Washington on C-SPAN 2. Here’s the schedule:  A Conversation with George Washington and Ben Franklin | Video | C-SPAN.org

Every year I look forward to FreedomFest, and this year’s event, scheduled for July 8-11, 2026, at the Caesars Forum Conference Center, is going to be memorable. We are billing it as “The World’s Fair of Liberty,” in honor of the 250th anniversary of our nation’s founding. 

You could also call it “The World Cup of Liberty”! 

First Things First!

Every FreedomFest, the first thing I do is get the printed program and circle all the breakout sessions I want to attend. You should do the same. You can get started now by going online at www.freedomfest.com/agenda and see the entire up-to-date program. There are over 200 sessions to choose from, including the Anthem film festival.

Wednesday, July 8: Let’s Get Started. 

It starts off at 11:30 – 11:45 am in rooms 110-112 with my wife Jo Ann and I highlighting the most exciting parts of FreedomFest and the Anthem film festival.  Come find a seat early!  Jo Ann has some great films as always that you won’t want to miss. Fit them into your schedule. You can see the entire list of films here:  Films – Anthem

“The Bestsellers of 1776”

Let’s lots to choose from on Wednesday afternoon. In my own case, I’ll start off FreedomFest at 12 noon hosting a series of breakout sessions in the Philosophers Room 104 entitled “The Bestsellers of 1776,” books and events that changed the world forever in 1776. The three sessions will be filmed by C-SPAN, and you are welcome to attend. Or watch them on C-SPAN in a few weeks. 

Session 1 at 12 – 12:45 pm will be on “The Two Toms: How Thomas Paine’s ‘Common Sense’ Led to Thomas Jefferson’s ‘Declaration of Independence,’” with guest historians David Fisher, Shane Krauser, and Randy . This will offer some great new insights into the American revolution.

Session 2 at 1 – 1:45 pm will be on “Adam Smith’s Wealth of Nations: The Declaration of Economic Independence,” with Rob Arnott, who will display his copy of the first edition of “The Wealth of Nations.” Worth seeing the two-volume work that changed the global economy.

Session 3 at 2 – 3 pm will be on “Edward Gibbon’s ‘Decline and Fall of the Roman Empire” and David Hume’s “Treatise on Human Nature,” with Steve Forbes (author of “Power Ambition Glory: The Stunning Parallels between Great Leaders of the Ancient World and Today”) and philosopher Brian Thomassen.  Gibbon’s 6-volume work foreshadowed the decline of the British empire, and Hume is considered the philosopher of the Enlightenment and Skepticism. A lively discussion!

What Should I Ask Senator Rand Paul?

Our opening ceremonies start right after this series, with a welcome from Valerie Durham, our conference director, and Kennedy (Fox News) as our emcee extraordinaire.  Actor Dean Cain (Superman in “Lois & Clark” series) will read the Declaration of Independence. We will also hear from Steve Forbes and others on “Celebrating the Achievements of the American Experiment: What Have We Done Right?”

At around 6 pm, I will interview Senator Rand Paul (the most libertarian senator today) on a variety of topics with “21 Questions.” Four years ago I interviewed Senator Paul, showing clips of his confrontations with various Biden administrators. Afterwards, he said it was the most fun interview he had ever had.

Would you like to ask Senator Paul a question? Send your question to me at [email protected], and I’ll see if can work it in.

Enjoy the Opening Cocktail Party and the Buzz in the Exhibit Hall

After his talk, the Opening Cocktail Party will begin and last until 8 pm. You won’t believe the buzz you will feel when you enter the Exhibit Hall.

Be sure to check out the Red Carpet appearance of our celebrity speakers, and take the opportunity to spend time with our exhibitors, including my new publisher, the Oxford Club (exhibit #310, right next to Battle Bank, my favorite new full-service online bank). Feel free to pick up a free copy of my new letter, The Skousen Report, and check out my new trading service, Future Tech Trader (co-edited by my son Tim), and other Oxford Club services. 

Don’t miss the “White Mates in Two” Chess Problem in the exhibit hall, always a favorite among attendees. First one to solve it gets a 2025 American eagle silver dollar, worth almost $100 these days!  A new chess problem will appear every day. 

Consider buying a silver dollar from our coin dealers there, and come up at the end of the closing panel on Saturday and get your picture taken with Steve Forbes and other speakers.  It’s always a highlight.

Ring the Liberty Bell!

And before you leave, be sure to make a contribution to the many free-market organizations and then go over ring the Liberty Bell, located at the Freedom360 Foundation Booth #419. It’s really loud!   

Thursday, July 9:  Debates and More

The following day, Thursday, I’ll be involved in several exciting events. At 8:30 – 9:15 am in the morning in the Adams Salon (Room 126), I’ll introduce neurosurgeon Michael Egnor, author of “The Immortal Mind,” who will give strong evidence and real-world experiences as a surgeon that the mind continues to live on while the brain does not.  Grab a quick breakfast, and join us.

After the early morning breakfast and sessions, we will start the main program with the Global Economic Summit, led by Rob Arnott, where global experts will discuss the current geo-political events in North and Latin America, the Middle East, Europe and Africa.

The morning general session will end with a revealing talk by Overstock CEO, Patrick Byrne, on “My Greatest Entrepreneurial Success: Disrupting the Deep State.”

Afterwards, Steve Forbes and I will be hosting a luncheon, Q&A, photo opportunity, and fundraiser with Senator Rand Paul and his wife Kelley. I suggest you sign up now, as the room only holds 120 people.  Be one of the lucky one! To sign up, go to www.freedomfest.com, and look for special events.

In the afternoon, we will have lots of breakout sessions and films, including a debate, “Is Trump a Net Gain or a Net Loss for Liberty?” with TV personality Wayne Allyn Root defending and Reason Senior Editor Jacob Sullum protesting the President. The sparks will fly. Epoch Times editor Jan Jekielek will be the moderator.

Founding Fathers Make an Appearance in “The Spirit of 1776” at the Coffee Break!

At 3 pm during the coffee break in the Exhibit Hall, watch for the original musical play “The Spirit of 1776” (written by Jo Ann Skousen) to appear with Steve Forbes as George Washington…Gary Alexander as John Adams….Dave Phillips as Roger Sherman….Brian Drury as Thomas Jefferson…Lydia Abbott as Martha Jefferson….and yours truly as Benjamin Franklin.  A 20-minute show not to be missed!  Get there early for a seat! 

Adam Carolla Interviews Nick Shirley, America’s #1 Investigative Report

Nick Shirley, our #1 keynote speaker this year, will be interviewed by Adam Carolla: “My Most Dangerous Assignment: Uncovering Government Fraud in Minnesota and California.” He has come under death threats and required additional security. Don’t miss his presentation.

Shirley met with Elon Musk, who awarded Shirley $100,000 to continue his expose of California fraud.

At 8 pm Thursday evening in the Anthem Film Festival Room 110-112, see “Reagan, The Director’s Cut,” and afterwards meet Sean McNamara the director and Mark Joseph the producer of this wonderful film about President Ronald Reagan, starring Dennis Quaid and Jon Voight.  

Friday, July 10

At 9 – 9:45 am in the Student Lounge Room 128, I will be speaking to several hundred students who are coming to FreedomFest (thanks to the donations of many) on the importance of “Austrian Economics for Students.”

Leonard E. “Read This Book” Award Goes to….

The main stage program begins at 9:30 am.  At 10:55 am, I will present this year’s Leonard E. “Read This Book” Award to historian and TV personality Eric Metaxas for his great book, “REVOLUTION: The Origins of the Greatest Nation in the History of the World” – a must read for all Americans as we celebrate the 250th anniversary of 1776.

After a short summary of the book, he will follow with a 45 minute in-depth discussion of his history at 2-2:45 pm Friday afternoon in the Free Speech Room #108-109, followed by an autograph session right afterwards in the Exhibit Hall from 2:45 – 3:45 pm (coffee break). See you in the exhibit hall, which John Mackey calls “The Trade Show for Liberty.” The buzz is incredible.

Mark Skousen and Eric Metaxas

Both Eric and I will be signing books, and we are going to have a contest to see who can sell the most copies, Eric’s “Revolution” or my “Greatest American.” Both books will be offered at a bargain price of $25.  Both will include a rare Franklin stamp. A collectible first edition!

Adam Smith vs Karl Marx:  The Ultimate Capitalism vs Socialism Debate!

Earlier that afternoon, at 1-1:45 pm in the Debate Room #106-107, I’ll be moderating a big capitalism vs socialism debate between John Mackey, former CEO of Whole Foods Market and author of “Conscious Capitalism,” and Marxist Professor Andrew Hartmann. “Resolved: Karl Marx’s critique of capitalism is fundamentally flawed; Free-enterprise capitalism is the greatest system ever invented to fulfill the needs of most members of society.” Can’t wait!

Glenn Beck, Then our Mock Trial on ICE!

I’m also looking forward to Glenn Beck’s talk on American history and his display of artifacts from the American Revolution. Afterwards, we will be hold this year’s mock trial will be a thriller, on the hottest topic today: Putting the Immigration and Customs Enforcement (ICE) on trial.

Our mock trial is always our most popular event. Our judge this year is American TV and film producer Del Bigtree, who led Robert F. Kennedy Jr.’s campaign for president in 2024. The prosecuting attorney is returning by popular demand: Atlanta criminal defense lawyer Catherine Bernard; the defense attorney will be TV personality and author Wayne Allyn Root. Star witnesses for the prosecution will be Athar Haseebullah, executive director of the ACLU in Nevada, and Billy Binion, top reporter for Reason magazine. Star witnesses for the defense will be actor and film producer Dean Cain, who played Superman in “Lois and Clark” TV series; and J. J. Carrell, a 24-year veteran of the U. S. Border Patrol in San Diego and author of “Invaded.” The 12 jurors will be selected from the audience. Majority rules. We have had a few cases of a hung jury (6-6). You won’t want to miss this year’s mock trial.

There will be a dinner that evening that everyone is invited to:  “The Freedom to Try” dinner sponsored by Dan Montano, with special guest speaker Bret Favre, former NFL quarterback!  Not to be missed!  The fee is $100 for a great evening.

Saturday, July 11 (7-11 in Vegas)

The last day of the big conference starts early with a 7:30 – 9:00 breakfast with the M&M Boys – Mark Skousen and Marc Lichtenfeld, both editors of the Oxford Club, with special guest Tim Skousen, co-editor of the Future Tech Trader.  Our topic:  “The Home Run Derby:  The M&M Boys Reveal their Favorite Growth & Income Hits.”  Sign up now, as this event is selling out.  It will be held in the Franklin Salon #102-103.  Of course!

UFC and Kelsey Grammer

In our main session on Saturday morning, we will meet the big names behind the UFC, including Brazilian fighter Renato Moicano, interviewed by Matt Kibbe, and then our keynote celebrity speaker, Kelsey Grammer, better known as “Frasier,” in an interview by Alexander McCobin, CEO of Principled Business and in charge of the Pitch Tank competition this year. Not to be missed!

After the coffee break, we’ll conclude with two closing panels, the “Washington Insiders Panel” with Steve Forbes, Grover Norquist, John Fund and Eric Erickson, followed by a second panel with Jon Nijarian, Terry Kibbe, Del Bigtree, and Rainer Zitelmann, author of the new book “New Space Capitalism.”

While the main stage and room will be broken down for the Saturday night banquet, we will have over a dozen breakout sessions to choose from, and even I will have a hard time deciding which to attend. At 2-2:45 pm in the Jefferson Room #124-125, we will have “The Free Will Debate: Are Humans Predictable and Rational, or Wayward and Incalculable?”  with Michael Shermer, Doug Jennifer Grossman, and Mark Skousen (moderator).

Before the Saturday night banquet, don’t miss the Anthem Champaigne Toast & Awards ceremony at 5-6 pm in the Anthem Film Festival Room 110-112.  Come early to get a seat!

And then come celebrate with us the Saturday night banquet, with lots of festivities, great food and drink, the annual Freedom Award to be given to Chris Rufer (“The Tomato King of California”), and dancing to the Quarter Millennials band.  A great way to end four days of celebrating liberty.

Next Year’s 20th Anniversary Celebration!

And don’t forget to sign up for next year’s FreedomFest, July 21-24, 2027, at Caesars Forum Conference Center, Las Vegas, where we will celebrate the 20th anniversary of “The Greatest Libertarian Show on Earth.”  Our theme is “Build the Rebellion.”  If we build it, they will come!

Yours for peace, prosperity, and liberty, AEIOU,

Dr. Mark Skousen

Filed Under: Articles, Featured article, Featured Post, Featured Story, Main

Good Sign: Business Spending is Finally Making a Comeback!

June 25, 2026 By Ned Piplovic Leave a Comment

“By integrating the vital role of the supply chain into national income accounting, Mark Skousen’s development of gross output (GO) has created a more dynamic and broader view of the economy, and of the central role that business plays in national income, the business cycle and economic growth. I recommend that economists seriously consider his new approach to macroeconomics.”

– Finn Kydland, Professor of Economics, University of California at Santa Barbara, 2004 Nobel prize winner

“It’s at least conceivable that gross output is a leading indicator of the economy.”

– Peter Coy, Economics Editor, New York Times (Aug 7, 2023)

Washington, DC (Thursday, June 25, 2026):

Today the federal government’s Bureau of Economic Analysis (BEA) released first quarter gross output (GO), the top-line that measures spending at all stages of production. Real Gross Output expanded 1.7%, which is a significant reversal from the 0.5% contraction from the last quarter of 2025, and indicates a positive outlook on economic growth heading into 2026. While real GO delivered a positive result compared to its own performance from the prior period, it did lag real GDP, which expanded 2.1% in the first period of 2026. When GO growth lags GDP growth, it generally indicates headwinds for economic expansion.

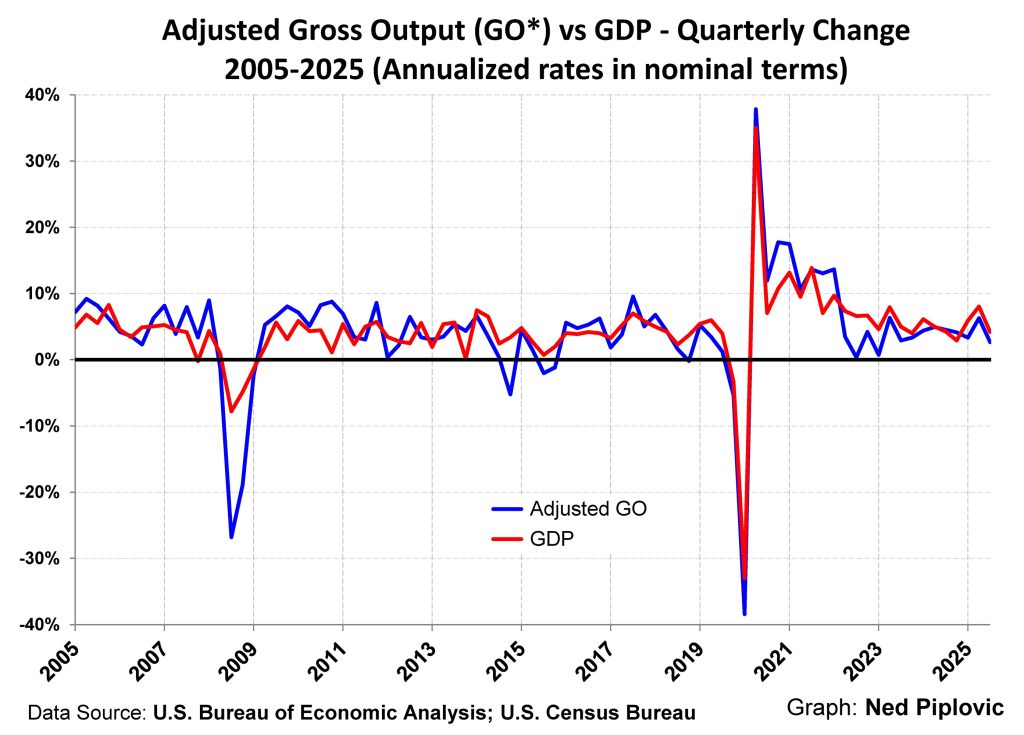
However, the adjusted Gross Output (GO*) outpaced GDP growth and delivered a 2.8% expansion for the same period, which supports economic expansion in the subsequent periods. While GO is sending a mixed message about forecasting the direction of the economy, the indicators present a significantly more optimistic outlook Q1 2026. Compared to the last period of 2025, when GO and GO* declined, both metrics increased at a brisk pace and GO* growth exceeded that of GDP.

The GO* surge was driven by a healthy uptick in Business-to-Business (B2B) spending in the first quarter, which increased 6.8% in inflation-adjusted terms and 10.6% in nominal terms. This indicates that the business sector either has confidence in economic growth over the near term or businesses are acquiring inventory in advance to hedge against potential price surges driven by any future inflation spikes resulting from geopolitical developments including ongoing U.S. military engagements in the Middle East. In contrast the inflation-adjusted consumer spending was essentially flat, with a lethargic increase of only 0.5%, and 5.2% in nominal terms.

The Federal Reserve (Fed) cut interest rates three times in the second half of 2025 for a total reduction of 75 basis points, which helped the job market expand slightly. With the unemployment rate stable in the 4.3%–4.4% range since December 2025, and the 2.1% real GDP growth, the Fed will have to decide whether the growth is driven by a solid economic foundation or is merely transitory. With Kevin Warsh sworn in as the new Fed Chair, we are eager to see how he will begin his tenure as chair of the central bank. While known for favoring easier monetary policies, the current economic growth is strong enough that it does not warrant a rate cut. The next Fed meeting is scheduled to begin on Monday June 29, and the general consensus is that the Fed will keep the rates most likely at the current levels, with a small chance of a quarter-point rate hike.

[1] The BEA currently uses a limited measure of total sales of goods and services in the production process. Once products are fabricated and packaged at the manufacturing stage, the BEA’s GO only adds “net” sales at the wholesale and retail level. Its official GO for the first quarter of 2026 is more than $54.7 trillion. By including gross sales at the wholesale and retail level, the Adjusted GO (GO*) expands to more than $66 trillion in Q1 2026. Thus, the BEA omits more than $11.5 trillion in business-to-business (B2B) transactions in its GO statistics. We include them as a legitimate economic activity that should be accounted for in GO, which we call Adjusted GO. See the new introduction to Mark Skousen, The Structure of Production, 3rd ed. (New York University Press, 2015), pp. xv-xvi.Unlike consumption, which maintains a steady long-term uptrend, business spending is significantly more volatile and more sensitive to economic fluctuations. Therefore, the reversal of business spending from the end of 2025 could indicate a higher level of confidence in the U.S. economy and a lower probability of a recession as we head towards mid-year. Business spending contracted in the last three periods of 2025, which might have been just a result of advance spending in Q1 in anticipation of higher tariffs. Therefore, while the Q1 surge sends a positive signal, we will need a confirmation of the trend in Q2 before we can conclude in more certain terms whether the increased B2B spending will continue and drive economic growth going forward.

The federal shutdown in October and November of last year, delayed the data release schedule and the BEA has been playing catch-up ever since then. However, it seems that the BEA has been able to catch up, as the current GO data release is happening at its usual time in late June. With the releases back on schedule, the Q2 data for GO will be available in late September.

GO as a Leading Indicator

In our model, GO – which includes the value of the supply chain – is a leading indicator of where the economy is headed in the year. When GO grows faster than GDP, it suggests economic expansion over the next few quarters, and vice versa. The BEA’s real GO expansion 1.7% trails the real GDP growth 2.1%. The static view indicates clearly that the economy might encounter some headwinds as we move deeper into 2026. However, the GO* growth of 2.8% outpacing the GDP expansion indicates substantial tailwinds that could propel the economy forward to continue expanding at a brisk pace. A quick resolution of the situation in Iran and the Strait of Hormuz would provide additional fuel to further accelerate economic growth in 2026.The Adjusted GO – which includes the gross wholesale and gross retail figures (included only as net figures in the GO reported by the BEA) – advanced 8.1% in nominal terms and has exceeded $66 trillion in the first quarter of 2026. The difference between net and gross figures amounts to more than $11.5 trillion, which is missing from the government’s official GO figure, but we include it in our Adjusted GO measure.

Our GO model has proven reliably more accurate than GDP in projecting the direction of the economy under normal circumstances. Economist and professor of applied economics at the Johns Hopkins University, Steve Hanke, stated that, “Trump’s trade wars throw another monkey wrench into the GDP metric,” and that, “for a reliable metric to take the economy’s temperature,” we should, “go with gross output.”

The Importance of GO

Most economists are still unaware of the value of GO and use only GDP when gauging economic outlook. However, gross output (GO) should be viewed as the top line in national income accounting, and GDP is the bottom line. Both metrics are essential to understanding where the economy is headed.

As Dale Jorgenson, Steve Landefeld, and William Nordhaus conclude in their book, A New Architecture for the U.S. National Accounts, “Gross output [GO] is the natural measure of the production sector, while net output [GDP] is appropriate as a measure of welfare. Both are required in a complete system of accounts.”

As Steve Forbes has suggested, “GDP is the X-ray of the economy; GO is the CAT-scan.”

Business – Not Consumers – Drives the Economy

Another benefit of GO is that it dispels the myth that consumer spending drives the economy. Contrary to views of many academic economists and wide-spread media reports, consumer spending does not represent two-thirds of total economic activity. Using GO as a better and a more accurate measure of total spending in the economy, the business sector (B2B spending) is almost twice the size of consumer spending. Consumer spending is the effect, not the cause, of prosperity (Say’s law).Therefore, our business-to-business (B2B) index is very useful for assessing the underlying health of the overall economy and its potential to bounce back after economic declines. The B2B Index measures all the business spending in the supply chain and new private capital investment. After expanding at a brisk 4.7% in Q3 2025, nominal B2B spending slowed growth to expand just 1.6% to $36.1 trillion in Q4 2025. In contrast, nominal consumer spending – which expanded 6.3% in the previous period – rose another 4.9% in Q4 to reach $21.4 trillion. The disparity is even bigger in real terms, where consumer spending rose 1.6%, but B2B contracted 2%. 

“B2B spending is in fact a pretty good indicator of where the economy is headed, since it is more responsive to the boom-bust economic cycle than consumer spending,” states Mark Skousen, editor of Forecasts & Strategies and the Doti-Spogli Chair of Free Enterprise at Chapman University.

While GDP includes only a small portion of investment spending, GO accounts for significantly more of the business investment outlays, which tend to indicate economic direction over extended periods. As David Ranson, chief economist for the private forecasting firm HCWE & Co., states, “Movements in gross output serve as a leading indicator of movements in GDP.”

The federal government will release the advance estimate for first-quarter 2026 GDP on April 30, 2026. Furthermore, the third estimate of GDP and the Gross output data for the first quarter of 2026 are scheduled to be released on June 25, 2026.

Important Note:  We are hopeful that in the near future, the BEA will release GO at the same time as the first estimate of GDP for the quarter, not the third estimate. We also recommend that GO be elevated in the BEA’s press releases and website as the “top line” in national income accounting, since GO data often tells a very different story than GDP data.

Report on Various Sectors of the Economy

Just like the overall economy struggled to expand, a third of the various economic segments contracted in the last quarter of 2025. After contracting six out of the past nine quarters and delivering a good 5.7% expansion in Q3 2025, the Agriculture sector ended the year with a solid 3.5% expansion in real terms. The Mining segment declined 3.7% after 4.2% expansion in Q3. After flat performance in the previous period, the Utilities segment grew 5.1% in Q4.

These three sectors account for less than 4% of the overall economy. However, since they occupy the earliest stages of production, they tend to be the foretellers of how the later stages – as well as the overall economy – might fare in the following few periods. While many other indicators show signs of a struggling economy in the immediate term, the solid growth in two out of these three segments might offer a more positive economic outlook in the more extended term. 

The Construction sector, which accounts for more than 4% of the economy, declined for a third consecutive period with a 5% contraction in Q4. Manufacturing, the second largest sector with more than 14% share of the overall economy, shrunk 3.1% in Q4 2025. Even more concerning is the overall structure of the contraction. While the nondurable goods sub-segment expanded 1.3%, the durable goods sub-segment contracted 7.2%, which is an indicator of potentially deeper structural concerns for long-term economic growth. The Wholesale and Retail trades expanded slower than in the previous period, but still delivered growth of 1.3% and 1.4%, respectively. However, The Transportation and Warehousing sub-segment reversed the 8% expansion from the previous period and contracted 5.6% in the last quarter of 2025.

The Information segment delivered another solid growth of 7.2% to make it four consecutive periods of expansion. The largest segment that accounts for nearly a fifth of the overall economy – Finance, insurance, real estate, rental, and leasing – expanded 2%, which followed three consecutive quarters of growth between 2.1% and 2.8%.

The Professional and business services sector reversed growth from the previous period and shrunk 2.7% in real terms. However, the Educational services, health care, and social assistance – which accounts for nearly 10% of the overall economy – tempered its growth of 6.3% from the previous quarter and expanded 2.7% in Q4. Within this segment, educational services contracted 1.3%, while health care and social services expanded 3.3%. The Arts, entertainment, recreation, accommodation, and food services sector remained unchanged overall. However, the arts, entertainment, and recreation, sub-segment expanded 4.8%, and the accommodation, and food services sub-segment declined 1.5%.

After contracting for two consecutive quarters to start 2025, total government spending followed up a 2.1% increase from Q3 2025 with a 4.7% contraction in the last quarter of 2025. The federal government spending cut of more than 18% drove the overall contraction of the segment. While federal government workers did receive back pay, some of this spending decline still might be the result of the October/November 2025 federal government shutdown. State and local government spending still increased nearly 2%.

Gross output (GO) and GDP are complementary statistics in national income accounting. GO is an attempt to measure the “make” economy; i.e., total economic activity at all stages of production, similar to the “top line” (revenues/sales) of a financial accounting statement. In April 2014, the BEA began to measure GO on a quarterly basis along with GDP.

Gross domestic product (GDP) is an attempt to measure the “use” economy, i.e., the value of finished goods and services ready to be used by consumers, businesses and government. GDP is not quite the same as the “bottom line” (profit, or net income) of an accounting statement, but rather the “value added” or the value of final use.

GO tends to be more sensitive to the business cycle, and more volatile, than GDP.

About GO and B2B Index

Skousen champions Gross Output as a more comprehensive measure of economic activity. “GDP leaves out the supply chain and business to business transactions in the production of intermediate inputs,” he notes. “That’s a big part of the economy, bigger than GDP itself. GO includes B2B activity that is vital to the production process. No one should ignore what is going on in the supply chain of the economy.”

Skousen first introduced Gross Output as a macroeconomic tool in his work The Structure of Production (New York University Press, 1990). A new third edition was published in late 2015 and is now available on Amazon.

Click here: Structure of Production on Amazon

The BEA’s decision in 2014 to publish GO on a quarterly basis in its “GDP by Industry” data is a major achievement in national income accounting. GO is the first output statistic to be published on a quarterly basis since GDP was invented in the 1940s.

The BEA now defines GDP in terms of GO. GDP is defined as “the value of the goods and services produced by the nation’s economy [GO] less the value of the goods and services used up in production (Intermediate Inputs or II].” See definitions at https://www.bea.gov/newsreleases/industry/gdpindustry/gdpindnewsrelease.htm

With GO and GDP being produced on a timely basis, the federal government now offers a complete system of accounts. As Dale Jorgenson, Steve Landefeld, and William Nordhaus conclude in their book, A New Architecture for the U. S. National Accounts, “Gross output [GO] is the natural measure of the production sector, while net output [GDP] is appropriate as a measure of welfare. Both are required in a complete system of accounts.”

Skousen adds, “Gross Output and GDP are complementary aspects of the economy, but GO does a better job of measuring total economic activity and the business cycle, and demonstrates that business spending is more significant than consumer spending,” he says. “By using GO data, we see that consumer spending is actually only about a third of economic activity, not two-thirds that is often reported by the media. As the chart above demonstrates, business spending is in fact almost twice the size of consumer spending in the US economy.”

For More Information

Best summary:  My paper, “GO Beyond GDP,” which explains what GO is all about, has been ranked the #1 most downloaded paper by the Social Science Research Network (SSRN). https://papers.ssrn.com/sol3/papers.cfm?abstract_id=5002052

The GO data released by the BEA can be found at www.bea.gov under “Quarterly GDP by Industry.” Click on interactive tables “GDP by Industry” and go to “Gross Output by Industry.” Or go to this link directly: https://apps.bea.gov/iTable/?reqid=150&step=2&isuri=1&categories=gdpxind

Mark Skousen, “Slow GO May Mean a Recession Soon” Wall Street Journal, April 4, 2024: https://www.wsj.com/articles/slow-go-may-mean-a-recession-soon-us-economy-real-gross-output-65c4f1fd?mod=commentary_article_pos3

Peter Coy, “What GDP’s Cousin Can Tell Us about the Economy,” August 7, 2023, New York Times:  https://www.nytimes.com/2023/08/07/opinion/gdp-recession-gross-output.html?searchResultPosition=1

Mark Skousen, “Recession Fears May Not Pass GO: GDP is Slumping, but There’s a Better Way to Gauge the Economy.” Wall Street Journal, August 11, 2022: Recession Fears May Not Pass GO – WSJ 

If you are not a WSJ subscriber, you can read a copy of the article on: https://www.grossoutput.com/2022/09/12/recession-fears-may-not-pass-go/

Emma Rothschild, “Where is Capital?” in Capitalism: A Journal of History and Economics 2:2 (Summer 2021), pp. 291-371.  https://muse.jhu.edu/article/798746   “Essentially an attempt to apply ideas about gross output to the economic history of the industrial revolution.”  

GO-Day podcast discussion panel hosted Mark Skousen that included Steve Forbes, Sean Flynn, Steve Hanke, and David Ranson, September 30, 2020: https://chapman.zoom.us/rec/share/KJ17YjuR_6zthmgOA5fNprv2e65F-jICOsf430bJvnu8qWzdPYPfTohPC48qRLe9.Q8rmnlXynnTN74Tv?startTime=1601488807000

Steve Forbes: What’s Ahead podcast. In this podcast, Steve Forbes discusses Gross Output with Mark Skousen on September 9, 2019; he compared GDP to an X-ray of the economy, and GO to a CAT-scan:  https://www.forbes.com/sites/steveforbes/2019/09/09/were-using-the-wrong-measure-gdp-to-gauge-the-economys-real-health-mark-skousen/#35ff3d9a52fa


For more information on Gross Output (GO), the Skousen B2B Index, and their relationship to GDP, see the following:

Mark Skousen, “If GDP Lags, Watch the Economy Grow,” Wall Street Journal, April 24, 2018:  https://www.grossoutput.com/2018/04/26/away-go-economy-growing-faster-expected/

Mark Skousen, “At Last, a Better Way to Economic Measure” lead editorial, Wall Street Journal, April 23, 2014: http://on.wsj.com/PsdoLM

Steve Forbes, Forbes Magazine (April 14, 2014): “New, Revolutionary Way To Measure The Economy Is Coming — Believe Me, This Is A Big Deal”: http://www.forbes.com/sites/steveforbes/2014/03/26/this-may-save-the-economoy-from-keynesians-and-spend-happy-pols/

Mark Skousen, Forbes Magazine (December 16, 2013): “Beyond GDP: Get Ready For A New Way To Measure The Economy”: http://www.forbes.com/sites/realspin/2013/11/29/beyond-gdp-get-ready-for-a-new-way-to-measure-the-economy/

Steve Hanke, Globe Asia (July 2014): “GO: J. M. Keynes Versus J.-B. Say,” http://www.cato.org/publications/commentary/go-jm-keynes-versus-j-b-say

David Ranson, “Output growth data that the economy generates months earlier than GDP,” Economy Watch, July 24, 2017. HCWE & Co. http://www.hcwe.com/guest/EW-0717.pdf

Mark Skousen, “Linking Austrian Economics to Keynesian Economics,” Journal of Private Enterprise, Winter, 2015: http://journal.apee.org/index.php?title=Parte7_Journal_of_Private_Enterprise_vol_30_no_4.pdf

To interview Dr. Mark Skousen on this press release, contact him at [email protected], or Ned Piplovic, Media Relations at [email protected].

# # #

Filed Under: Articles, Main

Fourth Quarter GO Confirms Deepening Stagflation into 2026

April 9, 2026 By Ned Piplovic Leave a Comment

“By integrating the vital role of the supply chain into national income accounting, Mark Skousen’s development of gross output (GO) has created a more dynamic and broader view of the economy, and of the central role that business plays in national income, the business cycle and economic growth. I recommend that economists seriously consider his new approach to macroeconomics.”

– Finn Kydland, Professor of Economics, University of California at Santa Barbara, 2004 Nobel prize winner

“It’s at least conceivable that gross output is a leading indicator of the economy.”

– Peter Coy, Economics Editor, New York Times (Aug 7, 2023)


Washington, DC (Thursday, April 9, 2026):

Today the federal government’s Bureau of Economic Analysis (BEA) released fourth quarter gross output (GO), the top-line that measures spending at all stages of production. Real Gross Output contracted 0.5%, which signals significant concerns about future economic growth. While real GDP expansion delivered a lethargic 0.5% growth, it remained positive, unlike GO. Both of these metrics indicate that the U.S. economy continues to face very strong headwinds against steady expansion. Economic data continues to signal that markets are fearful of President Trump’s continued trade war and the unrest in the Middle East.

Furthermore, after contracting 0.6% in Q1, growing merely 0.3% in Q2, and expanding just 1.1% in Q3, adjusted real Gross Output (GO*) contracted again 0.6% in Q4, as it did in Q1. Both GO and GO* increased slightly in Q3 but their growth lagged behind GDP, which indicated a struggle in the economy to advance at a faster pace. However, GO and GO* declining in Q4 sends a more concerning message – that despite marginal GDP growth, the economy is struggling to expand at all, and it is in real danger of contracting if the current geopolitical and economic environment persists.
After growing steadily around 2.5% in real terms during each of the two previous quarters, real consumer spending growth cooled off to 1.6% in the fourth quarter of 2025. However, the business sector – which tends to forecast economic outlook better than the consumer sector – contracted 2% in real terms on an annualized basis.
In the first half of 2025, the B2B spending decline might have been the result of retailers and suppliers purchasing of excess inventories during Q1 in anticipation that tariffs imposed by the Trump administration might result in price increases. However, that effect should have evaporated by the end of 2025. Therefore, the business decline at the end of the year carries a more significant concern about near-term business spending, which is the real driver of economic expansion.

Higher import tariffs generally increase consumer prices in the long run. Both headline and core inflation have declined in the first four months after the new administration took office in January 2025. However, since bottoming out at 2.3% in April 2025, monthly All-Items Consumer Price Index (CPI-U) published by the U.S. Bureau of Labor Statistics (BLS) has increased to 3% by the end of Q3 2025. While CPI data for October are not available because of the federal government shutdown and lapse in appropriations, the BLS reported the All-Items Consumer Price Index (CPI-U) holding steady at 2.7% for November and December 2025. January data shows CPI-U edging down further to 2.4%, which is at least one positive indicator.

The Federal Reserve (Fed) cut interest rates three times in the second half of 2025 for a total reduction of 75 basis points, which helped the job market expand slightly. After a recent peak of 4.6% in November 2025, the unemployment rate fell to 4.4 in December, and has remained in the 4.3%–4.4% range since then.

After three consecutive rate cuts, the Fed paused in early 2026 to evaluate the full impact on the economy of these recent cuts, as well as cumulative rate cuts of 175 basis points since late 2024. Advance GDP estimates for Q1 2026 indicated a relatively steady economic growth, which supported Fed’s decision to pause rate cuts in early 2026. However, with real GDP growth for Q4 2025 revised down from the advance estimate of 1.4% to just 0.5%, the Trump administration might lobby the Fed for additional cuts in 2026, especially if President Trump’s nominee – former member of the Federal Reserve Board of Governors Kevin Warsh – is confirmed and takes over from Jerome Powell as the Fed Chair in May.


[1] The BEA currently uses a limited measure of total sales of goods and services in the production process. Once products are fabricated and packaged at the manufacturing stage, the BEA’s GO only adds “net” sales at the wholesale and retail level. Its official GO for the fourth quarter of 2025 is more than $53.8 trillion. By including gross sales at the wholesale and retail level, the Adjusted GO (GO*) expands to nearly $65 trillion in Q4 2025. Thus, the BEA omits nearly $11.2 trillion in business-to-business (B2B) transactions in its GO statistics. We include them as a legitimate economic activity that should be accounted for in GO, which we call Adjusted GO. See the new introduction to Mark Skousen, The Structure of Production, 3rd ed. (New York University Press, 2015), pp. xv-xvi.

Gross Output


Unlike consumption, which maintains a steady long-term uptrend, business spending is significantly more volatile and more sensitive to economic fluctuations. Therefore, the sudden contraction of business spending could indicate a higher probability of a recession as we get deeper into 2026. While business spending contraction in early 2025 might have been just a result of advance spending in Q1 in anticipation of higher tariffs, the continued decline in the second half of the year is signaling potentially deeper structural causes of business spending contraction, that are less likely to be explained by inventory purchasing shifts.

We will need to wait until the BEA releases Q1 2026 data to get an indication whether B2B spending will reverse the trend and expand in early 2026. However, higher prices – especially energy prices that spiked due to the conflict in Iran – might dampen any business spending expansion that might otherwise have happened. The BEA’s data release schedule has been delayed due to the federal shutdown in October and November, and we have had to wait longer for quarterly data to become available. However, it seems that the BEA has worked through the backlog, and the Gross Output data release for first quarter of 2026 has been scheduled for its usual date in the last week of June.

GO as a Leading Indicator

In our model, GO – which includes the value of the supply chain – is a leading indicator of where the economy is headed in the year. When GO grows faster than GDP, it suggests economic expansion over the next few quarters, and vice versa. The BEA’s real GO contraction of 0.5% is trailing the real GDP expansion of 0.5%. The static view indicates clearly that the economy is facing headwinds entering 2026. While some irregularities in business spending patterns might have skewed the Q2 and Q3 data, the continued weakness in the last quarter of 2025 does not offer any clarity and raises concerns of weak economic outlook heading into 2026.


Gross Output

Unlike real terms that showed lethargic growth for GO and GO*, all three metrics expanded in nominal terms. GDP expanded at the highest pace of 4.2% and exceeded $31.4 trillion in Q4 2025. Nominal GO expanded at a slower pace than GDP and grew only 2.8% to reach $53.8 trillion.

The Adjusted GO – which includes the gross wholesale and gross retail figures (included only as net figures in the GO reported by the BEA) – advanced 2.7% in nominal terms and is currently just short of $65 trillion. The difference between net and gross figures amounts to more than $11.1 trillion, which is missing from the government’s official GO figure, but we include it in our Adjusted GO measure.

Our GO model has proven reliably more accurate than GDP in projecting the direction of the economy under normal circumstances. Economist and professor of applied economics at the Johns Hopkins University, Steve Hanke, stated that, “Trump’s trade wars throw another monkey wrench into the GDP metric,” and that, “for a reliable metric to take the economy’s temperature,” we should, “go with gross output.” Hanke also states that right now, “GO is flashing red.”

The Importance of GO

Most economists are still unaware of the value of GO and use only GDP when gauging economic outlook. However, gross output (GO) should be viewed as the top line in national income accounting, and GDP is the bottom line. Both metrics are essential to understanding where the economy is headed.

As Dale Jorgenson, Steve Landefeld, and William Nordhaus conclude in their book, A New Architecture for the U.S. National Accounts, “Gross output [GO] is the natural measure of the production sector, while net output [GDP] is appropriate as a measure of welfare. Both are required in a complete system of accounts.”

As Steve Forbes has suggested, “GDP is the X-ray of the economy; GO is the CAT-scan.”

Business – Not Consumers – Drives the Economy

Another benefit of GO is that it dispels the myth that consumer spending drives the economy. Contrary to views of many academic economists and wide-spread media reports, consumer spending does not represent two-thirds of total economic activity. Using GO as a better and a more accurate measure of total spending in the economy, the business sector (B2B spending) is almost twice the size of consumer spending. Consumer spending is the effect, not the cause, of prosperity (Say’s law).


Gross Output


Therefore, our business-to-business (B2B) index is very useful for assessing the underlying health of the overall economy and its potential to bounce back after economic declines. The B2B Index measures all the business spending in the supply chain and new private capital investment. After expanding at a brisk 4.7% in Q3 2025, nominal B2B spending slowed growth to expand just 1.6% to $36.1 trillion in Q4 2025. In contrast, nominal consumer spending – which expanded 6.3% in the previous period – rose another 4.9% in Q4 to reach $21.4 trillion. The disparity is even bigger in real terms, where consumer spending rose 1.6%, but B2B contracted 2%. 
“B2B spending is in fact a pretty good indicator of where the economy is headed, since it is more responsive to the boom-bust economic cycle than consumer spending,” states Mark Skousen, editor of Forecasts & Strategies and the Doti-Spogli Chair of Free Enterprise at Chapman University.

While GDP includes only a small portion of investment spending, GO accounts for significantly more of the business investment outlays, which tend to indicate economic direction over extended periods. As David Ranson, chief economist for the private forecasting firm HCWE & Co., states, “Movements in gross output serve as a leading indicator of movements in GDP.”

The federal government will release the advance estimate for first-quarter 2026 GDP on April 30, 2026. Furthermore, the third estimate of GDP and the Gross output data for the first quarter of 2026 are scheduled to be released on June 25, 2026.

Important Note:  We are hopeful that in the near future, the BEA will release GO at the same time as the first estimate of GDP for the quarter, not the third estimate. We also recommend that GO be elevated in the BEA’s press releases and website as the “top line” in national income accounting, since GO data often tells a very different story than GDP data.

Report on Various Sectors of the Economy

Just like the overall economy struggled to expand, a third of the various economic segments contracted in the last quarter of 2025. After contracting six out of the past nine quarters and delivering a good 5.7% expansion in Q3 2025, the Agriculture sector ended the year with a solid 3.5% expansion in real terms. The Mining segment declined 3.7% after 4.2% expansion in Q3. After flat performance in the previous period, the Utilities segment grew 5.1% in Q4.

These three sectors account for less than 4% of the overall economy. However, since they occupy the earliest stages of production, they tend to be the foretellers of how the later stages – as well as the overall economy – might fare in the following few periods. While many other indicators show signs of a struggling economy in the immediate term, the solid growth in two out of these three segments might offer a more positive economic outlook in the more extended term. 

The Construction sector, which accounts for more than 4% of the economy, declined for a third consecutive period with a 5% contraction in Q4. Manufacturing, the second largest sector with more than 14% share of the overall economy, shrunk 3.1% in Q4 2025. Even more concerning is the overall structure of the contraction. While the nondurable goods sub-segment expanded 1.3%, the durable goods sub-segment contracted 7.2%, which is an indicator of potentially deeper structural concerns for long-term economic growth. The Wholesale and Retail trades expanded slower than in the previous period, but still delivered growth of 1.3% and 1.4%, respectively. However, The Transportation and Warehousing sub-segment reversed the 8% expansion from the previous period and contracted 5.6% in the last quarter of 2025.

The Information segment delivered another solid growth of 7.2% to make it four consecutive periods of expansion. The largest segment that accounts for nearly a fifth of the overall economy – Finance, insurance, real estate, rental, and leasing – expanded 2%, which followed three consecutive quarters of growth between 2.1% and 2.8%.

The Professional and business services sector reversed growth from the previous period and shrunk 2.7% in real terms. However, the Educational services, health care, and social assistance – which accounts for nearly 10% of the overall economy – tempered its growth of 6.3% from the previous quarter and expanded 2.7% in Q4. Within this segment, educational services contracted 1.3%, while health care and social services expanded 3.3%. The Arts, entertainment, recreation, accommodation, and food services sector remained unchanged overall. However, the arts, entertainment, and recreation, sub-segment expanded 4.8%, and the accommodation, and food services sub-segment declined 1.5%.

After contracting for two consecutive quarters to start 2025, total government spending followed up a 2.1% increase from Q3 2025 with a 4.7% contraction in the last quarter of 2025. The federal government spending cut of more than 18% drove the overall contraction of the segment. While federal government workers did receive back pay, some of this spending decline still might be the result of the October/November 2025 federal government shutdown. State and local government spending still increased nearly 2%.

Gross output (GO) and GDP are complementary statistics in national income accounting. GO is an attempt to measure the “make” economy; i.e., total economic activity at all stages of production, similar to the “top line” (revenues/sales) of a financial accounting statement. In April 2014, the BEA began to measure GO on a quarterly basis along with GDP.

Gross domestic product (GDP) is an attempt to measure the “use” economy, i.e., the value of finished goods and services ready to be used by consumers, businesses and government. GDP is not quite the same as the “bottom line” (profit, or net income) of an accounting statement, but rather the “value added” or the value of final use.

GO tends to be more sensitive to the business cycle, and more volatile, than GDP.

About GO and B2B Index

Skousen champions Gross Output as a more comprehensive measure of economic activity. “GDP leaves out the supply chain and business to business transactions in the production of intermediate inputs,” he notes. “That’s a big part of the economy, bigger than GDP itself. GO includes B2B activity that is vital to the production process. No one should ignore what is going on in the supply chain of the economy.”

Skousen first introduced Gross Output as a macroeconomic tool in his work The Structure of Production (New York University Press, 1990). A new third edition was published in late 2015 and is now available on Amazon.

Click here: Structure of Production on Amazon

The BEA’s decision in 2014 to publish GO on a quarterly basis in its “GDP by Industry” data is a major achievement in national income accounting. GO is the first output statistic to be published on a quarterly basis since GDP was invented in the 1940s.

The BEA now defines GDP in terms of GO. GDP is defined as “the value of the goods and services produced by the nation’s economy [GO] less the value of the goods and services used up in production (Intermediate Inputs or II].” See definitions at https://www.bea.gov/newsreleases/industry/gdpindustry/gdpindnewsrelease.htm

With GO and GDP being produced on a timely basis, the federal government now offers a complete system of accounts. As Dale Jorgenson, Steve Landefeld, and William Nordhaus conclude in their book, A New Architecture for the U. S. National Accounts, “Gross output [GO] is the natural measure of the production sector, while net output [GDP] is appropriate as a measure of welfare. Both are required in a complete system of accounts.”

Skousen adds, “Gross Output and GDP are complementary aspects of the economy, but GO does a better job of measuring total economic activity and the business cycle, and demonstrates that business spending is more significant than consumer spending,” he says. “By using GO data, we see that consumer spending is actually only about a third of economic activity, not two-thirds that is often reported by the media. As the chart above demonstrates, business spending is in fact almost twice the size of consumer spending in the US economy.”

For More Information

Best summary:  My paper, “GO Beyond GDP,” which explains what GO is all about, has been ranked the #1 most downloaded paper by the Social Science Research Network (SSRN). https://papers.ssrn.com/sol3/papers.cfm?abstract_id=5002052

The GO data released by the BEA can be found at www.bea.gov under “Quarterly GDP by Industry.” Click on interactive tables “GDP by Industry” and go to “Gross Output by Industry.” Or go to this link directly: https://apps.bea.gov/iTable/?reqid=150&step=2&isuri=1&categories=gdpxind

Mark Skousen, “Slow GO May Mean a Recession Soon” Wall Street Journal, April 4, 2024: https://www.wsj.com/articles/slow-go-may-mean-a-recession-soon-us-economy-real-gross-output-65c4f1fd?mod=commentary_article_pos3

Peter Coy, “What GDP’s Cousin Can Tell Us about the Economy,” August 7, 2023, New York Times:  https://www.nytimes.com/2023/08/07/opinion/gdp-recession-gross-output.html?searchResultPosition=1

Mark Skousen, “Recession Fears May Not Pass GO: GDP is Slumping, but There’s a Better Way to Gauge the Economy.” Wall Street Journal, August 11, 2022: Recession Fears May Not Pass GO – WSJ 

If you are not a WSJ subscriber, you can read a copy of the article on: https://www.grossoutput.com/2022/09/12/recession-fears-may-not-pass-go/

Emma Rothschild, “Where is Capital?” in Capitalism: A Journal of History and Economics 2:2 (Summer 2021), pp. 291-371.  https://muse.jhu.edu/article/798746   “Essentially an attempt to apply ideas about gross output to the economic history of the industrial revolution.”  

GO-Day podcast discussion panel hosted Mark Skousen that included Steve Forbes, Sean Flynn, Steve Hanke, and David Ranson, September 30, 2020: https://chapman.zoom.us/rec/share/KJ17YjuR_6zthmgOA5fNprv2e65F-jICOsf430bJvnu8qWzdPYPfTohPC48qRLe9.Q8rmnlXynnTN74Tv?startTime=1601488807000

Steve Forbes: What’s Ahead podcast. In this podcast, Steve Forbes discusses Gross Output with Mark Skousen on September 9, 2019; he compared GDP to an X-ray of the economy, and GO to a CAT-scan:  https://www.forbes.com/sites/steveforbes/2019/09/09/were-using-the-wrong-measure-gdp-to-gauge-the-economys-real-health-mark-skousen/#35ff3d9a52fa


For more information on Gross Output (GO), the Skousen B2B Index, and their relationship to GDP, see the following:

Mark Skousen, “If GDP Lags, Watch the Economy Grow,” Wall Street Journal, April 24, 2018:  https://www.grossoutput.com/2018/04/26/away-go-economy-growing-faster-expected/

Mark Skousen, “At Last, a Better Way to Economic Measure” lead editorial, Wall Street Journal, April 23, 2014: http://on.wsj.com/PsdoLM

Steve Forbes, Forbes Magazine (April 14, 2014): “New, Revolutionary Way To Measure The Economy Is Coming — Believe Me, This Is A Big Deal”: http://www.forbes.com/sites/steveforbes/2014/03/26/this-may-save-the-economoy-from-keynesians-and-spend-happy-pols/

Mark Skousen, Forbes Magazine (December 16, 2013): “Beyond GDP: Get Ready For A New Way To Measure The Economy”: http://www.forbes.com/sites/realspin/2013/11/29/beyond-gdp-get-ready-for-a-new-way-to-measure-the-economy/

Steve Hanke, Globe Asia (July 2014): “GO: J. M. Keynes Versus J.-B. Say,” http://www.cato.org/publications/commentary/go-jm-keynes-versus-j-b-say

David Ranson, “Output growth data that the economy generates months earlier than GDP,” Economy Watch, July 24, 2017. HCWE & Co. http://www.hcwe.com/guest/EW-0717.pdf

Mark Skousen, “Linking Austrian Economics to Keynesian Economics,” Journal of Private Enterprise, Winter, 2015: http://journal.apee.org/index.php?title=Parte7_Journal_of_Private_Enterprise_vol_30_no_4.pdf

To interview Dr. Mark Skousen on this press release, contact him at [email protected], or Ned Piplovic, Media Relations at [email protected].

# # #

Filed Under: Articles, Main

The Divided Economy: Business Still Trying to Catch Up to the Consumer Boom

January 22, 2026 By Ned Piplovic Leave a Comment

“By integrating the vital role of the supply chain into national income accounting, Mark Skousen’s development of gross output (GO) has created a more dynamic and broader view of the economy, and of the central role that business plays in national income, the business cycle and economic growth. I recommend that economists seriously consider his new approach to macroeconomics.”

– Finn Kydland, Professor of Economics, University of California at Santa Barbara, 2004 Nobel prize winner

“It’s at least conceivable that gross output is a leading indicator of the economy.”

– Peter Coy, Economics Editor, New York Times (Aug 7, 2023)


Washington, DC (Thursday, January 22, 2026):

Today the federal government’s Bureau of Economic Analysis (BEA) released third quarter gross output (GO), the top-line that measures spending at all stages of production. Real Gross Output expanded 3.2%, which is generally a positive sign of future economic growth. However, real GO growth lagged slightly behind the real GDP expansion of 4.4%, which is an indicator of an economy struggling to expand at full speed. Economic data suggests that market fears of Trump’s trade war are waning slightly, but continue to restrain the economy from expanding at full speed.
However, while GO growth lagged behind GDP in Q3, both indicators performed significantly better than in the first two quarters of 2025. Furthermore, while contracting 0.6% in Q1 and growing only 0.3% in Q2 for a flat cumulative performance in the first half of the year. Adjusted real gross output (GO*) expanded 1.1% the third quarter. While all three metrics – GDP, GO and GO* – expanded in the third quarter, the fact that GO and GO* are growing slower than GDP raises concerns about economic growth, at least in the near term.

After slowing its growth to a mere 0.4% in Q1 2025 and expanding 2.6% in the second quarter, consumer spending continued its real-terms growth at 2.5% in the third quarter of 2025. The business sector – which tends to forecast economic outlook better than the consumer sector – contracted for a second consecutive period. However, the 1.8% contraction in the third quarter was significantly less than the 5.6% real-term contraction from the previous period. This second consecutive pullback is small enough and seems to be going in the right direction. If this trend continues, business spending should resume its steady expansion trend as it had for four consecutive periods before the brief contraction over the last two quarters.
One of the reasons for the B2B spending decline might be still the effects of retailers and suppliers purchasing of excess inventories during Q1 in anticipation that tariffs imposed by the Trump administration might result in price increases. While businesses have worked through and exhausted some of those excess inventories, enough inventory remains to warrant a decline in business spending. Therefore, those advance purchases in Q1 still affected the business sector spending in Q3, which resulted in a lower GO growth.

Abraham Lincoln stated in his 1858 Illinois Republican Senate nomination speech, “A house divided against itself cannot stand.” Similarly, an economy with an imbalance of rising consumer spending and declining business spending cannot expand over the long term. However, just as Lincoln did not “expect the house to fall” in his speech, the economy must sort itself out to create conditions for a sustained long-term growth. To do that, either consumer spending has to dry up, or business spending must catch up. Hopefully the latter.
Higher import tariffs generally increase consumer prices in the long run. Both headline and core inflation have declined in the first four months after the new administration took office in January 2025. However, since bottoming out at 2.3% in April 2025, monthly All-Items Consumer Price Index (CPI-U) published by the U.S. Bureau of Labor Statistics (BLS) has increased to 3% by the end of Q3 2025. While CPI data for October are not available because of the federal government shutdown and lapse in appropriations, the BLS reported the All-Items Consumer Price Index (CPI-U) at 2.7% for November and December 2025.

After cutting interest rates at its September 17 meeting, the Federal Reserve (Fed) has followed up with two additional short-term rate cuts in November and December, for a total rate cut of 50 basis points in the last quarter of 2025. While the lower interest rates helped the job market growth, the unemployment rate increased slightly to reach 4.4% by the end of 2025.

While President Trump seems to have gotten his wish of at least a few rate cuts, the Fed will most likely pause any rate cuts in early 2026, to see the full impact on the economy of the 175 basis points cumulative rate cut since late 2024. However, markets will certainly be cautious in anticipation who the new Fed Chairman will be, as Jerome Powell’s term as the Fed Chair is set to expire in May 2026.

The leading candidates for the Chair position include the National Economic Council Director Kevin Hassett, BlackRock, Inc.’s Chief Investment Officer Rick Rieder, Fed Governor Christopher Waller, and former member of the Federal Reserve Board of Governors Kevin Warsh. Regardless of which person gets the job, the new Fed Chair likely to be more inclined towards looser money policies than Jerome Powell, which could yield additional interest rate cuts in the second half of 2026, unless economic growth picks up speed by then.

[1] The BEA currently uses a limited measure of total sales of goods and services in the production process. Once products are fabricated and packaged at the manufacturing stage, the BEA’s GO only adds “net” sales at the wholesale and retail level. Its official GO for the third quarter of 2025 is nearly $53.5 trillion. By including gross sales at the wholesale and retail level, the Adjusted GO (GO*) expands to more than $63.8 trillion in Q3 2025. Thus, the BEA omits nearly $10.4 trillion in business-to-business (B2B) transactions in its GO statistics. We include them as a legitimate economic activity that should be accounted for in GO, which we call Adjusted GO. See the new introduction to Mark Skousen, The Structure of Production, 3rd ed. (New York University Press, 2015), pp. xv-xvi.

Gross Output


Unlike consumption, which maintains a steady long-term uptrend, business spending is significantly more volatile and more sensitive to economic fluctuations. Therefore, the sudden contraction of business spending could indicate a higher probability of a recession in the second half of 2025 or early 2026. However, as indicated earlier, the B2B spending decline in Q2 might have been just a result of advance spending in Q1. While business spending still contracted, the Q3 contraction was significantly smaller than the Q2 decline. This might indicate that business spending might be stabilizing.

We will need to wait until the BEA releases Q4 and full-year 2025 data to get clearer insight into B2B spending trends for early 2026. Due to the federal shutdown in October and November, the BEA’s data release schedule has been delayed, and the specific release date for Q4 data release has not been announced.

GO as a Leading Indicator

In our model, GO – which includes the value of the supply chain – is a leading indicator of where the economy is headed in the year. When GO grows faster than GDP, it suggests economic expansion over the next few quarters, and vice versa. Currently, the BEA’s real GO growth rate of 3.2% is significantly lower than the annualized Real GDP growth of 4.4%. The static view might indicate that the economy is facing headwinds entering 2026. However, some irregularities in business spending patterns might have skewed the Q2 and Q3 data. Hopefully, the fourth-quarter data will offer more clarity regarding the economic outlook leading deeper into 2026.


Gross Output

After sending mixed signals regarding the direction of the economy during 2024, the current economic data for the first three quarters of 2025 is equally ambiguous, and does not provide any more certainty regarding the economic growth outlook for the extended future. The fourth-quarter 2025 GO data, will hopefully give a clearer indication of the economic direction.
Unlike real terms that showed lethargic growth for GO and especially GO*, all three metrics expanded relatively well in nominal terms. GDP expanded at the highest pace of 8.3% to exceed $31 trillion for the first time ever. GO trailed GDP growth only slightly, and expanded 7.0% to reach $53.5 trillion.


The Adjusted GO – which includes the gross wholesale and gross retail figures (included only as net figures in the GO reported by the BEA) – advanced just 1.1% in nominal terms the third-quarter of 2025 and currently stands at $63.8 trillion. The difference between net and gross figures amounts to more than $10.4 trillion, which is missing from the government’s official GO figure, but we include it in our Adjusted GO measure.

Our GO model has proven reliably more accurate than GDP in projecting the direction of the economy under normal circumstances. Economist and professor of applied economics at the Johns Hopkins University, Steve Hanke, stated that as, “Trump’s trade wars throw another monkey wrench into the GDP metric,” and that, “for a reliable metric to take the economy’s temperature,” we should, “go with gross output.” Hanke also states that right now, “GO is flashing red.”

The Importance of GO

Most economists are still unaware of the value of GO and use only GDP when gauging economic outlook. However, gross output (GO) should be viewed as the top line in national income accounting, and GDP is the bottom line. Both metrics are essential to understanding where the economy is headed.

As Dale Jorgenson, Steve Landefeld, and William Nordhaus conclude in their book, A New Architecture for the U. S. National Accounts, “Gross output [GO] is the natural measure of the production sector, while net output [GDP] is appropriate as a measure of welfare. Both are required in a complete system of accounts.”

As Steve Forbes has suggested, “GDP is the X-ray of the economy; GO is the CAT-scan.” 

Business – Not Consumers – Drives the Economy

Another benefit of GO is that it dispels the myth that consumer spending drives the economy. Contrary to views of many academic economists and wide-spread media reports, consumer spending does not represent two-thirds of total economic activity. Using GO as a better and a more accurate measure of total spending in the economy, the business sector (B2B spending) is almost twice the size of consumer spending. Consumer spending is the effect, not the cause, of prosperity (Say’s law).


Gross Output

Therefore, our business-to-business (B2B) index is very useful for assessing the underlying health of the overall economy and its potential to bounce back after economic declines. The B2B Index measures all the business spending in the supply chain and new private capital investment. After contracting 3.6% in Q2 2025, nominal B2B spending reversed direction and expanded 1.9% to $35.2 trillion in Q3 2025. In contrast, nominal consumer spending followed as 3.7% expansion from a previous period with a 6.3% surge in Q3 to reach $21.1 trillion. The disparity is even bigger in real terms, where consumer spending rose 2.5%, but B2B contracted 1.8%.

“B2B spending is in fact a pretty good indicator of where the economy is headed, since it is more responsive to the boom-bust economic cycle than consumer spending,” states Mark Skousen, editor of Forecasts & Strategies and the Doti-Spogli Chair of Free Enterprise at Chapman University.
While GDP includes only a small portion of investment spending, GO accounts for significantly more of the business investment outlays, which tend to indicate economic direction over extended periods. As David Ranson, chief economist for the private forecasting firm HCWE & Co., states, “Movements in gross output serve as a leading indicator of movements in GDP.”
The federal government will release the advance estimate for third-quarter 2025 GDP on February 20, 2026. Because of the federal government shutdown last fall, the date for the full release of Q4 Gross Output data not been set yet. However, the current BEA data release schedule seems to be running about a month behind normal. Therefore, we should see the Q4 GO data, as well as the third estimate of GDP, release no later than mid-to-late April 2026.

Important Note:  We are hopeful that in the near future, the BEA will release GO at the same time as the first estimate of GDP for the quarter, not the third estimate. We also recommend that GO be elevated in the BEA’s press releases and website as the “top line” in national income accounting, since GO data often tells a very different story than GDP data.

Report on Various Sectors of the Economy

Just like the overall economy continues to deliver mixed signals, the various segments of the economy are equally volatile. After contracting six out of the past eight quarters, the Agriculture sector surged 5.7% in the third-quarter 2025. The Mining segment reversed a brief contraction from a previous period with a 4.2% expansion in Q3. After surging 11.6% in Q1 2025 and a 7% decline in Q2 2025, the Utilities segment remained flat in Q3 2025.
These three sectors account for less than 4% of the overall economy. However, since they occupy the earliest stages of production, they tend to be the foretellers of how the later stages, as well as the overall economy might fare in the following few periods.

The Construction sector, which accounts for more than 4% of the economy, declined nearly 6% in Q3. This continued the downtrend after contracting slightly at 0.6% in the first quarter of 2025, and shrinking 2.4% in Q2 2025 in real terms. Manufacturing, the second largest sector with more than 14% share of the overall economy, expanded 1% in Q3 2025. While the overall segment expanded only slightly, the structure of the expansion might indicate a potential for a positive near-term outlook.


While the nondurable goods segment contracted 2.1%, the durable goods sub-segment delivered a 4.1% growth, which is an even wider gap than it was in the previous period, and a better positive indicator for long term growth. The Wholesale trade reversed its 10.7% decline in the second-quarter and expanded 7.8% in Q3 2025. After contracting for two consecutive periods, the Retail trade expanded 5% in the third quarter. The Transportation and Warehousing reversed a contraction from Q1 and a small expansion in Q2, with an 8% expansion in Q3 2025.


After two periods of double-digit growth, the Information segment tempered its expansion to just 2.8% in the most recent period. The largest segment that accounts for nearly a fifth of the overall economy – Finance, insurance, real estate, rental, and leasing – delivered a 2.1% expansion in real terms, which was in line with the 2.5%, and 2.8% growth from the first two periods of 2025.

The Professional and business services sector; and the Educational services, health care, and social assistance – which account combined for more than 21% of the overall economy – expanded 6.6% and 6.3%, respectively. These growth rates are approximately 50% higher than in the previous period. After contracting 4.3% in Q1 and surging 7.7% in Q2, the Arts, entertainment, recreation, accommodation, and food services sector expanded at more moderate rate of 1.5% in Q3.

After contracting for two consecutive quarters to start 2025, total government spending increased 2.1% in Q3 2025. The growth was divided evenly between a 2.1% growth of federal government spending, and 2.0% expansion of State and local spending.

Gross output (GO) and GDP are complementary statistics in national income accounting. GO is an attempt to measure the “make” economy; i.e., total economic activity at all stages of production, similar to the “top line” (revenues/sales) of a financial accounting statement. In April 2014, the BEA began to measure GO on a quarterly basis along with GDP.

Gross domestic product (GDP) is an attempt to measure the “use” economy, i.e., the value of finished goods and services ready to be used by consumers, business and government. GDP is not quite the same as the “bottom line” (profit, or net income) of an accounting statement, but rather the “value added” or the value of final use.

GO tends to be more sensitive to the business cycle, and more volatile, than GDP.

About GO and B2B Index

Skousen champions Gross Output as a more comprehensive measure of economic activity. “GDP leaves out the supply chain and business to business transactions in the production of intermediate inputs,” he notes. “That’s a big part of the economy, bigger than GDP itself. GO includes B2B activity that is vital to the production process. No one should ignore what is going on in the supply chain of the economy.”

Skousen first introduced Gross Output as a macroeconomic tool in his work The Structure of Production (New York University Press, 1990). A new third edition was published in late 2015 and is now available on Amazon.

Click here: Structure of Production on Amazon

The BEA’s decision in 2014 to publish GO on a quarterly basis in its “GDP by Industry” data is a major achievement in national income accounting. GO is the first output statistic to be published on a quarterly basis since GDP was invented in the 1940s.

The BEA now defines GDP in terms of GO. GDP is defined as “the value of the goods and services produced by the nation’s economy [GO] less the value of the goods and services used up in production (Intermediate Inputs or II].” See definitions at https://www.bea.gov/newsreleases/industry/gdpindustry/gdpindnewsrelease.htm

With GO and GDP being produced on a timely basis, the federal government now offers a complete system of accounts. As Dale Jorgenson, Steve Landefeld, and William Nordhaus conclude in their book, A New Architecture for the U. S. National Accounts, “Gross output [GO] is the natural measure of the production sector, while net output [GDP] is appropriate as a measure of welfare. Both are required in a complete system of accounts.”

Skousen adds, “Gross Output and GDP are complementary aspects of the economy, but GO does a better job of measuring total economic activity and the business cycle, and demonstrates that business spending is more significant than consumer spending,” he says. “By using GO data, we see that consumer spending is actually only about a third of economic activity, not two-thirds that is often reported by the media. As the chart above demonstrates, business spending is in fact almost twice the size of consumer spending in the US economy.”

For More Information

This just in:  My paper, “GO Beyond GDP,” which explains what GO is all about, has been ranked the #1 most downloaded paper by the Social Science Research Network (SSRN). https://papers.ssrn.com/sol3/papers.cfm?abstract_id=5002052

The GO data released by the BEA can be found at www.bea.gov under “Quarterly GDP by Industry.” Click on interactive tables “GDP by Industry” and go to “Gross Output by Industry.” Or go to this link directly: https://apps.bea.gov/iTable/?reqid=150&step=2&isuri=1&categories=gdpxind

Mark Skousen, “Slow GO May Mean a Recession Soon” Wall Street Journal, April 4, 2024: https://www.wsj.com/articles/slow-go-may-mean-a-recession-soon-us-economy-real-gross-output-65c4f1fd?mod=commentary_article_pos3

Peter Coy, “What GDP’s Cousin Can Tell Us about the Economy,” August 7, 2023, New York Times:  https://www.nytimes.com/2023/08/07/opinion/gdp-recession-gross-output.html?searchResultPosition=1

Mark Skousen, “Recession Fears May Not Pass GO: GDP is Slumping, but There’s a Better Way to Gauge the Economy.” Wall Street Journal, August 11, 2022: Recession Fears May Not Pass GO – WSJ 

If you are not a WSJ subscriber, you can read a copy of the article on: https://www.grossoutput.com/2022/09/12/recession-fears-may-not-pass-go/

Emma Rothschild, “Where is Capital?” in Capitalism: A Journal of History and Economics 2:2 (Summer 2021), pp. 291-371.  https://muse.jhu.edu/article/798746   “Essentially an attempt to apply ideas about gross output to the economic history of the industrial revolution.”  

GO-Day podcast discussion panel hosted Mark Skousen that included Steve Forbes, Sean Flynn, Steve Hanke, and David Ranson, September 30, 2020: https://chapman.zoom.us/rec/share/KJ17YjuR_6zthmgOA5fNprv2e65F-jICOsf430bJvnu8qWzdPYPfTohPC48qRLe9.Q8rmnlXynnTN74Tv?startTime=1601488807000

Steve Forbes: What’s Ahead podcast. In this podcast, Steve Forbes discusses Gross Output with Mark Skousen on September 9, 2019; he compared GDP to an X-ray of the economy, and GO to a CAT-scan:  https://www.forbes.com/sites/steveforbes/2019/09/09/were-using-the-wrong-measure-gdp-to-gauge-the-economys-real-health-mark-skousen/#35ff3d9a52fa


For more information on Gross Output (GO), the Skousen B2B Index, and their relationship to GDP, see the following:

Mark Skousen, “If GDP Lags, Watch the Economy Grow,” Wall Street Journal, April 24, 2018:  https://www.grossoutput.com/2018/04/26/away-go-economy-growing-faster-expected/

Mark Skousen, “At Last, a Better Way to Economic Measure” lead editorial, Wall Street Journal, April 23, 2014: http://on.wsj.com/PsdoLM

Steve Forbes, Forbes Magazine (April 14, 2014): “New, Revolutionary Way To Measure The Economy Is Coming — Believe Me, This Is A Big Deal”: http://www.forbes.com/sites/steveforbes/2014/03/26/this-may-save-the-economoy-from-keynesians-and-spend-happy-pols/

Mark Skousen, Forbes Magazine (December 16, 2013): “Beyond GDP: Get Ready For A New Way To Measure The Economy”: http://www.forbes.com/sites/realspin/2013/11/29/beyond-gdp-get-ready-for-a-new-way-to-measure-the-economy/

Steve Hanke, Globe Asia (July 2014): “GO: J. M. Keynes Versus J.-B. Say,” http://www.cato.org/publications/commentary/go-jm-keynes-versus-j-b-say

David Ranson, “Output growth data that the economy generates months earlier than GDP,” Economy Watch, July 24, 2017. HCWE & Co. http://www.hcwe.com/guest/EW-0717.pdf

Mark Skousen, “Linking Austrian Economics to Keynesian Economics,” Journal of Private Enterprise, Winter, 2015: http://journal.apee.org/index.php?title=Parte7_Journal_of_Private_Enterprise_vol_30_no_4.pdf

To interview Dr. Mark Skousen on this press release, contact him at [email protected], or Ned Piplovic, Media Relations at [email protected].

# # #

Filed Under: Articles, Main

Trump Trade War Hits Business: Economy Slows to a Crawl

September 25, 2025 By Ned Piplovic Leave a Comment

“By integrating the vital role of the supply chain into national income accounting, Mark Skousen’s development of gross output (GO) has created a more dynamic and broader view of the economy, and of the central role that business plays in national income, the business cycle and economic growth. I recommend that economists seriously consider his new approach to macroeconomics.”

– Finn Kydland, Professor of Economics, University of California at Santa Barbara, 2004 Nobel prize winner

“It’s at least conceivable that gross output is a leading indicator of the economy.”

– Peter Coy, Economics Editor, New York Times (Aug 7, 2023)


Washington, DC (Thursday, September 25, 2025):

Today the federal government’s Bureau of Economic Analysis (BEA) released 2nd quarter gross output (GO), the top-line that measures spending at all stages of production. Real Gross Output expanded 1.2%, which is generally a positive sign of future economic growth. However, real GO growth lagged significantly behind the real GDP expansion of 3.8%, which is an indicator of an economy struggling to expand at full speed. Economic data seems to be indicating that Trump’s trade war is finally having deliriously negative effects on business.


However, while GO growth lagged behind GDP in Q2, both indicators performed significantly better in Q2 than in the previous period when real GDP contracted and real GO expanded only 0.6% – only half the rate of current growth. The Adjusted real gross output (GO*) is the worst performer with a real-term growth of only 0.3% in the second quarter. However, that is still a positive outcome compared to the 0.6% contraction in the first quarter 2025.

After faltering a bit in the previous period, consumers spending returned to a steady growth trend and expanded in the second quarter 3.8% in real terms. However, the concern is the 5.6% real-term contraction of the business sector – which tends to forecast economic outlook better than the consumer sector. This is the first pullback in business spending after four consecutive periods of steady growth.

One of the reasons for the B2B spending decline could be the effects of retailers and suppliers purchasing of excess inventories during Q1 in anticipation that tariffs imposed by the Trump administration might result in price increases. Therefore, after those purchases in advance, the business sector tapered its spending in Q2, which resulted in a lower GO growth.

Higher import tariffs generally increase consumer prices in the long run. Both headline and core inflation have declined in the first four months after the new administration took office in January 2025. However, since bottoming out at 2.3% in April 2025, monthly All-Items Consumer Price Index (CPI-U) published by the U.S. Bureau of Labor Statistics (BLS) has increased to 2.9%.


President Trump has been lobbying strongly for an immediate interest rate cut potentially to mitigate some of the negative economic impact of the increased tariffs. At its September 17, the Federal Reserve (Fed) cut the its short-term rates because, “uncertainty about the economic outlook remains elevated,” as well as because, “downside risks to employment have risen.” While President Trump seems to have gotten his wish, the Fed cut the rates only a quarter of a point, instead of a half a point that the current administration preferred. However, while still taking a wait-and-see approach, the Fed has signaled that it might cut the rates two more time before 2025 is over.

[1] The BEA currently uses a limited measure of total sales of goods and services in the production process. Once products are fabricated and packaged at the manufacturing stage, the BEA’s GO only adds “net” sales at the wholesale and retail level. Its official GO for the second quarter of 2025 is nearly $52.6 trillion. By including gross sales at the wholesale and retail level, the Adjusted GO (GO*) expands to more than $63.3 trillion in Q2 2025. Thus, the BEA omits almost $11 trillion in business-to-business (B2B) transactions in its GO statistics. We include them as a legitimate economic activity that should be accounted for in GO, which we call Adjusted GO. See the new introduction to Mark Skousen, The Structure of Production, 3rd ed. (New York University Press, 2015), pp. xv-xvi.

Gross Output


Unlike consumption, which maintains a steady uptrend over the long term, business spending is significantly more volatile and more sensitive to economic fluctuations. Therefore, the sudden contraction of business spending could indicate a higher probability of a recession in the second half of 2025 or early 2026. However, as indicated earlier, the B2B spending decline in Q2 might be just a result of advance spending in Q1.
We will have to wait until the BEA releases Q3 GO data in late December be certain whether the Q2 B2B spending contraction is just a temporary blip or a beginning of a longer trend, as well as to have a better indication of the economy’s potential trajectory over the next few periods.

GO as a Leading Indicator

In our model, GO – which includes the value of the supply chain – is a leading indicator of where the economy is headed in the year. When GO grows faster than GDP, it suggests economic expansion over the next few quarters, and vice versa. Currently, the BEA’s real GO growth rate of 1.2% is significantly lower than the annualized Real GDP growth of 3.8%. The static view might indicate that the economy is facing headwinds in the second half of 2025. However, some irregularities in business spending patterns might have skewed the Q2 data. Hopefully, the third quarter data in December will offer more clarity regarding the economic outlook at the end of 2025 and leading into 2026.

Gross Output


After sending mixed signals regarding the direction of the economy during 2024, the current economic data for the first two quarters of 2025 is equally ambiguous, and does not provide any more certainty regarding the economic growth outlook for the extended future. The third-quarter 2025 GO data, which is scheduled for release in late December, will hopefully give a clearer indication of the economic direction.
Unlike real terms that showed lethargic growth for GO and especially GO*, all three metrics expanded relatively well in nominal rems. GDP expanded at the highest pace of 3.8% to exceed $30 trillion for the first time ever. GO made modest progress and rose 3.2% to $52.6 trillion.

The Adjusted GO – which includes the gross wholesale and gross retail figures (included only as net figures in the GO reported by the BEA) – advanced just 2.3% in nominal terms the second-quarter 2025 and currently stands at $62.2 trillion. The difference between net and gross figures amounts to nearly $11 trillion, which is missing from the government’s official GO figure, but we include it in our Adjusted GO measure.

Our GO model has proven reliably more accurate than GDP in projecting the direction of the economy under normal circumstances. Economist and professor of applied economics at the Johns Hopkins University, Steve Hanke, stated that as, “Trump’s trade wars throw another monkey wrench into the GDP metric,” and that, “for a reliable metric to take the economy’s temperature,” we should, “go with gross output.” Hanke also states that right now, “GO is flashing red.”

The Importance of GO

Most economists are still unaware of the value of GO and use only GDP when gauging economic outlook. However, gross output (GO) should be viewed as the top line in national income accounting, and GDP is the bottom line. Both metrics are essential to understanding where the economy is headed.

As Dale Jorgenson, Steve Landefeld, and William Nordhaus conclude in their book, A New Architecture for the U. S. National Accounts, “Gross output [GO] is the natural measure of the production sector, while net output [GDP] is appropriate as a measure of welfare. Both are required in a complete system of accounts.”

As Steve Forbes has suggested, “GDP is the X-ray of the economy; GO is the CAT-scan.” 

Business – Not Consumers – Drives the Economy

Another benefit of GO is that it dispels the myth that consumer spending drives the economy. Contrary to views of many academic economists and wide-spread media reports, consumer spending does not represent two-thirds of total economic activity. Using GO as a better and a more accurate measure of total spending in the economy, the business sector (B2B spending) is almost twice the size of consumer spending. Consumer spending is the effect, not the cause, of prosperity (Say’s law).

Gross Output


Therefore, our business-to-business (B2B) index is very useful for assessing the underlying health of the overall economy and its potential to bounce back after economic declines. The B2B Index measures all the business spending in the supply chain and new private capital investment. After expanding at an average rate of approximately 4% in 2024 and surging 6.7% in Q1 2025, nominal B2B spending pulled back 3.6% from $35.5 trillion in Q1 to $35.2 trillion in Q2 2025. In contrast, after being relatively flat in Q1, nominal consumer spending expanded 3.7% to $20.5 trillion. The disparity is similar in real terms, where consumer spending rose 2.6%, but B2B contracted 5.6%.

“B2B spending is in fact a pretty good indicator of where the economy is headed, since it is more responsive to the boom-bust economic cycle than consumer spending,” states Mark Skousen, editor of Forecasts & Strategies and the Doti-Spogli Chair of Free Enterprise at Chapman University.
While GDP includes only a small portion of investment spending, GO accounts for significantly more of the business investment outlays, which tend to indicate economic direction over extended periods. As David Ranson, chief economist for the private forecasting firm HCWE & Co., states, “Movements in gross output serve as a leading indicator of movements in GDP.”
The federal government will release the advance estimate for third-quarter 2025 GDP on October 30, 2025. The full release of Q3 Gross Output data, as well as the third estimate of GDP are scheduled for December 19, 2025.

Important Note:  We are hopeful that in the near future, the BEA will release GO at the same time as the first estimate of GDP for the quarter, not the third estimate. We also recommend that GO be elevated in the BEA’s press releases and website as the “top line” in national income accounting, since GO data often tells a very different story than GDP data.

Report on Various Sectors of the Economy

Just like the overall economy continues to deliver mixed signals, the various segments of the economy are equally volatile. After contracting six out of the past seven quarters, the Agriculture sector remained flat in the second-quarter 2025. The Mining segment followed expansions of approximately 1% in the previous two periods with a 0.6% contraction in the current period. After staying relatively flat in the last quarter of 2024 and surging 11.6% in Q1 2025, the Utilities segment declined nearly 7% in the second-quarter 2025.
These three sectors account for less than 4% of the overall economy. However, since they occupy the earliest stages of production, they tend to be the foretellers of how the later stages, as well as the overall economy might fare in the following few periods.

The Construction sector, which accounts for more than 4% of the economy and contracted slightly at 0.6% in the first quarter of 2025, widened the contraction in Q2 2025 and declined 2.4% in real terms. The second largest sector – accounting for 14% of the overall economy – built on a 0.3% contraction from the previous quarter with a 1.9% expansion Q2 2025. While the overall segment expanded only slightly, the structure of the expansion might indicate a potential for a positive near-term outlook.
While the nondurable goods segment contracted expanded 1%, the durable goods sub-segment delivered a 2.7% growth, which is a better positive indicator for long term growth. The Wholesale trade followed two growth periods with a 10.7% decline in the second-quarter 2025. While higher growth of the durable goods sub-segment and the wholesale trade generally indicate a positive outlook near-term economic growth, it appears that the high growth in Q1 was at least partially the result of business purchasing inventories and goods in advance to hedge for the anticipation of tariff-driven price increases.

Therefore, the sharp decline in the Wholesale trade in Q2 resulted partially from some of the spending occurring in Q1 After declining 3.5% in Q1 2025, the Retail trade contracted even further and fell 7.1% in the second-quarter 2025. The Transportation and Warehousing reversed a 3.7% contraction from the previous period and expanded 2.1% for the most recent period.

The Information backed an 11.6% surge in Q1 with a nearly equal expansion of 10.1% in Q2 2025. The largest segment that accounts for nearly a fifth of the overall economy – Finance, insurance, real estate, rental, and leasing – delivered a 22.8% expansion in real terms, which was in line with the 2.5% growth from the first quarter.

The Professional and business services sector; and the Educational services, health care, and social assistance – which account combined for more than 21% of the overall economy – expanded 4.7% and 4.6%, respectively. After contracting 4.3% in Q1, the Arts, entertainment, recreation, accommodation, and food services sector reversed direction and surged 7.7% in the most recent period.

After three consecutive periods of expansion to end 2024, total government spending followed a 0.6% contraction with another overall decline in the second-quarter 2025. Federal government spending decline of 6% drove the overall reduction in government spending. However, despite the strong spending reduction on the federal level and because State and local spending accounts for two-thirds of total government spending, the state and local spending increase of 1.6% reduced the total government spending contraction to 0.7% in Q2 2025.

Gross output (GO) and GDP are complementary statistics in national income accounting. GO is an attempt to measure the “make” economy; i.e., total economic activity at all stages of production, similar to the “top line” (revenues/sales) of a financial accounting statement. In April 2014, the BEA began to measure GO on a quarterly basis along with GDP.

Gross domestic product (GDP) is an attempt to measure the “use” economy, i.e., the value of finished goods and services ready to be used by consumers, business and government. GDP is not quite the same as the “bottom line” (profit, or net income) of an accounting statement, but rather the “value added” or the value of final use.

GO tends to be more sensitive to the business cycle, and more volatile, than GDP.

About GO and B2B Index

Skousen champions Gross Output as a more comprehensive measure of economic activity. “GDP leaves out the supply chain and business to business transactions in the production of intermediate inputs,” he notes. “That’s a big part of the economy, bigger than GDP itself. GO includes B2B activity that is vital to the production process. No one should ignore what is going on in the supply chain of the economy.”

Skousen first introduced Gross Output as a macroeconomic tool in his work The Structure of Production (New York University Press, 1990). A new third edition was published in late 2015 and is now available on Amazon.

Click here: Structure of Production on Amazon

The BEA’s decision in 2014 to publish GO on a quarterly basis in its “GDP by Industry” data is a major achievement in national income accounting. GO is the first output statistic to be published on a quarterly basis since GDP was invented in the 1940s.

The BEA now defines GDP in terms of GO. GDP is defined as “the value of the goods and services produced by the nation’s economy [GO] less the value of the goods and services used up in production (Intermediate Inputs or II].” See definitions at https://www.bea.gov/newsreleases/industry/gdpindustry/gdpindnewsrelease.htm

With GO and GDP being produced on a timely basis, the federal government now offers a complete system of accounts. As Dale Jorgenson, Steve Landefeld, and William Nordhaus conclude in their book, A New Architecture for the U. S. National Accounts, “Gross output [GO] is the natural measure of the production sector, while net output [GDP] is appropriate as a measure of welfare. Both are required in a complete system of accounts.”

Skousen adds, “Gross Output and GDP are complementary aspects of the economy, but GO does a better job of measuring total economic activity and the business cycle, and demonstrates that business spending is more significant than consumer spending,” he says. “By using GO data, we see that consumer spending is actually only about a third of economic activity, not two-thirds that is often reported by the media. As the chart above demonstrates, business spending is in fact almost twice the size of consumer spending in the US economy.”

For More Information

This just in:  My paper, “GO Beyond GDP,” which explains what GO is all about, has been ranked the #1 most downloaded paper by the Social Science Research Network (SSRN). https://papers.ssrn.com/sol3/papers.cfm?abstract_id=5002052

The GO data released by the BEA can be found at www.bea.gov under “Quarterly GDP by Industry.” Click on interactive tables “GDP by Industry” and go to “Gross Output by Industry.” Or go to this link directly: https://apps.bea.gov/iTable/?reqid=150&step=2&isuri=1&categories=gdpxind

Mark Skousen, “Slow GO May Mean a Recession Soon” Wall Street Journal, April 4, 2024: https://www.wsj.com/articles/slow-go-may-mean-a-recession-soon-us-economy-real-gross-output-65c4f1fd?mod=commentary_article_pos3

Peter Coy, “What GDP’s Cousin Can Tell Us about the Economy,” August 7, 2023, New York Times:  https://www.nytimes.com/2023/08/07/opinion/gdp-recession-gross-output.html?searchResultPosition=1

Mark Skousen, “Recession Fears May Not Pass GO: GDP is Slumping, but There’s a Better Way to Gauge the Economy.” Wall Street Journal, August 11, 2022: Recession Fears May Not Pass GO – WSJ 

If you are not a WSJ subscriber, you can read a copy of the article on: https://www.grossoutput.com/2022/09/12/recession-fears-may-not-pass-go/

Emma Rothschild, “Where is Capital?” in Capitalism: A Journal of History and Economics 2:2 (Summer 2021), pp. 291-371.  https://muse.jhu.edu/article/798746   “Essentially an attempt to apply ideas about gross output to the economic history of the industrial revolution.”  

GO-Day podcast discussion panel hosted Mark Skousen that included Steve Forbes, Sean Flynn, Steve Hanke, and David Ranson, September 30, 2020: https://chapman.zoom.us/rec/share/KJ17YjuR_6zthmgOA5fNprv2e65F-jICOsf430bJvnu8qWzdPYPfTohPC48qRLe9.Q8rmnlXynnTN74Tv?startTime=1601488807000

Steve Forbes: What’s Ahead podcast. In this podcast, Steve Forbes discusses Gross Output with Mark Skousen on September 9, 2019; he compared GDP to an X-ray of the economy, and GO to a CAT-scan: :  https://www.forbes.com/sites/steveforbes/2019/09/09/were-using-the-wrong-measure-gdp-to-gauge-the-economys-real-health-mark-skousen/#35ff3d9a52fa


For more information on Gross Output (GO), the Skousen B2B Index, and their relationship to GDP, see the following:

Mark Skousen, “If GDP Lags, Watch the Economy Grow,” Wall Street Journal, April 24, 2018:  https://www.grossoutput.com/2018/04/26/away-go-economy-growing-faster-expected/

Mark Skousen, “At Last, a Better Way to Economic Measure” lead editorial, Wall Street Journal, April 23, 2014: http://on.wsj.com/PsdoLM

Steve Forbes, Forbes Magazine (April 14, 2014): “New, Revolutionary Way To Measure The Economy Is Coming — Believe Me, This Is A Big Deal”: http://www.forbes.com/sites/steveforbes/2014/03/26/this-may-save-the-economoy-from-keynesians-and-spend-happy-pols/

Mark Skousen, Forbes Magazine (December 16, 2013): “Beyond GDP: Get Ready For A New Way To Measure The Economy”: http://www.forbes.com/sites/realspin/2013/11/29/beyond-gdp-get-ready-for-a-new-way-to-measure-the-economy/

Steve Hanke, Globe Asia (July 2014): “GO: J. M. Keynes Versus J.-B. Say,” http://www.cato.org/publications/commentary/go-jm-keynes-versus-j-b-say

David Ranson, “Output growth data that the economy generates months earlier than GDP,” Economy Watch, July 24, 2017. HCWE & Co. http://www.hcwe.com/guest/EW-0717.pdf

Mark Skousen, “Linking Austrian Economics to Keynesian Economics,” Journal of Private Enterprise, Winter, 2015: http://journal.apee.org/index.php?title=Parte7_Journal_of_Private_Enterprise_vol_30_no_4.pdf

To interview Dr. Mark Skousen on this press release, contact him at [email protected], or Ned Piplovic, Media Relations at [email protected].

# # #

Filed Under: Articles, Featured Story, Main

Consumers Are Cautious at the Start Of 2025, but Businesses Show Confidence in Near-Term Growth.

June 26, 2025 By Ned Piplovic 4 Comments

Washington, DC (Thursday, June 26, 2025):

Today the federal government’s Bureau of Economic Analysis (BEA) released 1st quarter gross output (GO), the top-line that measures spending at all stages of production. Real Gross Output expanded 0.6%. GO expansion is generally a positive sign of future economic growth. However, real GDP contracted 0.5%, which indicates that consumers are concerned about the U.S. economy’s ability to expand in the near-term. Furthermore, consumer reluctance drove real consumer spending in Q1 2025 to be lower than the previous period, which resulted in the Adjusted real gross output (GO*) contracting 0.6%. While delivering a positive result in nominal terms, the real-term GDP and GO* decline casts some doubts regarding which direction the economy will take as we head into the second half of the year. Despite these real-term declines of GDP and GO*, GO growth leading GDP growth generally indicates a positive economic outlook. Furthermore, while consumers are concerned, the business sector – which tends to forecast economic outlook better than the consumer sector – sees something positive in the current economy to warrant a significant expansion of Business-to-Business (B2B) spending in the first quarter of the year. However, the B2B spending increase most likely is the result of retailers and suppliers advance purchasing of excess inventories in anticipation of rising prices because of the new tariffs imposed by the Trump administration.
The main business concern coming onto 2025 was the uncertainty about the impact that the new Trump administration’s policies might have on the overall economy. While rising import tariffs generally increase consumer prices in the long run, both headline and core inflation have continued to decline after the new administration took office in January 2025, but exhibited a small increase in May. Since it takes a little time for structural changes to occur in the economy to adjust to the new reality of higher tariffs, we must be on the lookout to see whether this inflation uptick in May was a temporary blip, or a beginning of a reversal that will see prices continue to increase as a consequence of the new import tariff policies.

President Trump has been lobbying for an immediate interest rate cut to mitigate potentially some of the negative economic impact of the increased tariffs. However, the Federal Reserve (Fed) decided to keep the interest rates unchanged at its most recent meeting on June 17 and June 18. Responding to criticism by some Congress Republicans, Fed Chair Jerome Powell indicated that the Fed – as well as most economists and financial experts – still expect that the higher tariffs will push inflation higher in the near term. Therefore, the Fed is taking a wait-and-see approach.

Testifying before the House Financial Services Committee, Powell stated, “For the time being, we are well positioned to wait to learn more about the likely course of the economy before considering any adjustments to our policy stance.” Therefore, the Fed decided to maintain the current interest at the 4.25%-4.50%, but is still open to the possibility of two quarter-percentage-point cuts in 2025, if rising tariffs and prices drive the economy to reverse direction and take a downturn in late 2025.

While we see no near-term resolution to the Ukraine war, the new and potentially bigger concern now is the impact of the Trump Administration’s recent bombing of Iran’s nuclear facilities, as well as any potential retaliation by the Iranian government – as well as independent extremists’ organizations. However, even if there is no direct retaliation, we will not see the effects of these economic concerns in GDP and GO data until the BEA releases that data much later in the year.

Unlike consumption, which maintains a steady uptrend over the long term, business spending is significantly more volatile and more sensitive to economic fluctuations. Therefore, the slowly increasing business spending growth over the past several quarters, could indicate also that we might be safe from a recession, and on the way towards a steady economic expansion.

[1] The BEA currently uses a limited measure of total sales of goods and services in the production process. Once products are fabricated and packaged at the manufacturing stage, the BEA’s GO only adds “net” sales at the wholesale and retail level. Its official GO for the first quarter of 2025 is slightly more than $52 trillion. By including gross sales at the wholesale and retail level, the Adjusted GO (GO*) expands to nearly $62.8 trillion in Q1 2025. Thus, the BEA omits almost $11 trillion in business-to-business (B2B) transactions in its GO statistics. We include them as a legitimate economic activity that should be accounted for in GO, which we call Adjusted GO. See the new introduction to Mark Skousen, The Structure of Production, 3rd ed. (New York University Press, 2015), pp. xv-xvi.

Gross Output

GO as a Leading Indicator

In our model, GO – which includes the value of the supply chain – is a leading indicator of where the economy is headed in the year. When GO grows faster than GDP, it suggests economic expansion over the next few quarters, and vice versa. Currently, the BEA’s real GO* growth rate of 0.6 % is higher than the annualized Real GDP contraction of 0.5%. The static view might indicate that the economy is facing headwinds entering 2025. However, the fourth quarter metrics do not paint a clear picture.

Gross Output

After sending mixed signals regarding the direction of the economy since the beginning of 2024, the current economic data for the Q1 2025 is equally ambiguous, and does not provide any more certainty regarding the economic growth outlook for the extended future. The second-quarter 2025 GO data is scheduled to be released in late September, which will hopefully give a clearer indication of the economic direction for the rest of 2025.
Unlike real terms that showed a decline for two of the three metrics. All three metrics expanded in nominal rems. GDP expanded at the slowest pace of 3.2% to reach $29.96 trillion. GO made the largest progress and rose 4.7% to exceed $52 trillion for the first time ever.

The Adjusted GO – which includes the gross wholesale and gross retail figures (included only as net figures in the GO reported by the BEA) – advanced 3.4% in nominal terms at the end of the first-quarter 2025 and currently exceeds $62 trillion. The difference between net and gross figures amounts to nearly $11 trillion, which is missing from the government’s official GO figure, but we include it in our Adjusted GO measure.

Our GO model has proven reliably accurate in projecting the direction of GDP under normal economic circumstances.

The Importance of GO

Most economists are still unaware of the value of GO and use only GDP when gauging economic outlook. However, gross output (GO) should be viewed as the top line in national income accounting, and GDP is the bottom line. Both metrics are essential to understanding where the economy is headed.

As Dale Jorgenson, Steve Landefeld, and William Nordhaus conclude in their book, A New Architecture for the U. S. National Accounts, “Gross output [GO] is the natural measure of the production sector, while net output [GDP] is appropriate as a measure of welfare. Both are required in a complete system of accounts.”

As Steve Forbes has suggested, “GDP is the X-ray of the economy; GO is the CAT-scan.” 

Business – Not Consumers – Drives the Economy

Another benefit of GO is that it dispels the myth that consumer spending drives the economy. Contrary to views of many academic economists and wide-spread media reports, consumer spending does not represent two-thirds of total economic activity. Using GO as a better and a more accurate measure of total spending in the economy, the business sector (B2B spending) is almost twice the size of consumer spending. Consumer spending is the effect, not the cause, of prosperity (Say’s law).Gross Output

Therefore, our business-to-business (B2B) index is very useful for assessing the underlying health of the overall economy and its potential to bounce back after economic declines. The B2B Index measures all the business spending in the supply chain and new private capital investment. After expanding at an average rate of approximately 4% in 2024, nominal B2B spending accelerated growth and expanded 6.7% in Q1 2025, which pushed the annualized B2B spending to more than $35 trillion. In contrast, after expanding in excess of 5.3% for 2024, nominal consumer spending expanded just 1% in the first quarter of 2025. The disparity is even more visible in real terms, where consumer spending experienced no growth whatsoever, but B2B expanded 1.6% – the highest real B2B expansion since Q2 2022.

“B2B spending is in fact a pretty good indicator of where the economy is headed, since it is more responsive to the boom-bust economic cycle than consumer spending,” states Mark Skousen, editor of Forecasts & Strategies and the Doti-Spogli Chair of Free Enterprise at Chapman University.
While GDP includes only a small portion of investment spending, GO accounts for significantly more of the business investment outlays, which tend to indicate economic direction over extended periods. As David Ranson, chief economist for the private forecasting firm HCWE & Co., states, “Movements in gross output serve as a leading indicator of movements in GDP.”
The federal government will release the advance estimate for second-quarter 2025 GDP on July 30, 2025. The full release of Q2 Gross Output data, as well as the third estimate of GDP are scheduled for September 25, 2025.

.

Important Note:  We are hopeful that in the near future, the BEA will release GO at the same time as the first estimate of GDP for the quarter, not the third estimate. We also recommend that GO be elevated in the BEA’s press releases and website as the “top line” in national income accounting, since GO data often tells a very different story than GDP data.

Report on Various Sectors of the Economy

Just like the overall economy delivered mixed signals, the various segments of the economy followed suit. After breaking a trend of declining for five consecutive quarters in real terms, the Agriculture sector followed up last period’s marginal expansion of 0.3% with a major reversal and contracted 12.2% in the first quarter of 2025. The Mining segment delivered a second consecutive expansion, and rose 1.1% following a 0.8% growth in the previous quarter. The Utilities segment built on a small 0.6% expansion from Q4 2024, and surged 11.6% in Q1 2025.
These three sectors account for less than 4% of the overall economy. However, since they occupy the earliest stages of production, they tend to be the foretellers of how the later stages, as well as the overall economy might fare in the following few periods.

The Construction sector, which accounts for more than 4% of the economy and expanded 3.7% in the last quarter of 2024, contracted slightly at 0.6% in the first quarter of 2025. The second largest sector – accounting for 14% of the overall economy – reversed its small contraction from the previous quarter and expanded 0.3% in Q1 2025. However, while the overall segment expanded only slightly, the structure of the expansion might indicate a potential for a positive near-term outlook. While the nondurable goods segment contracted 0.7%, the durable goods sub-segment delivered a 1.2% growth. The Wholesale trade followed a 2% growth from the previous period with another, albeit smaller expansion of 0.5%. While higher growth of the durable goods sub-segment and the wholesale trade generally indicates a positive outlook near-term economic growth, we must keep in mind that this might be merely a result of the advance inventory purchases in anticipation of tariff-driven price increases.

Upcoming data releases might shed some light on whether advanced purchasing of excess inventories might have driven the Wholesale trade to expand. However, the Retail trade reversed its expansion of 6.4% from Q4 2024, and declined 3.5% in Q1 2025. The Transportation and Warehousing contracted similarly at 3.7% for the period.

After growing only 1% in Q4 2024 following a 7.9% expansion in Q3, the Information sector surged 11.6% to kick of 2025. The largest segment that accounts for nearly a fifth of the overall economy – Finance, insurance, real estate, rental, and leasing – delivered a sizeable expansion of 2.5% in Q1 2025, after growing only 0.3% in the last quarter of 2024.
The Professional and business services sector; and the Educational services, health care, and social assistance – which account combined for more than 21% of the overall economy – expanded 0.2%, 2.8%, respectively. However, after delivering a positive result in the previous period, the Arts, entertainment, recreation, accommodation, and food services sector took a dive and contracted 4.3%.
After expanding for three consecutive periods, total government spending contracted in the first period of 2025. State and local governments, which account for two-thirds of total government spending still expanded 2.3%. However, despite being only one-third of the overall government spending, federal government spending declined significantly enough – 7.2% – to make the total government spending shrink 0.6%

Gross output (GO) and GDP are complementary statistics in national income accounting. GO is an attempt to measure the “make” economy; i.e., total economic activity at all stages of production, similar to the “top line” (revenues/sales) of a financial accounting statement. In April 2014, the BEA began to measure GO on a quarterly basis along with GDP.

Gross domestic product (GDP) is an attempt to measure the “use” economy, i.e., the value of finished goods and services ready to be used by consumers, business and government. GDP is not quite the same as the “bottom line” (profit, or net income) of an accounting statement, but rather the “value added” or the value of final use.

GO tends to be more sensitive to the business cycle, and more volatile, than GDP.

About GO and B2B Index

Skousen champions Gross Output as a more comprehensive measure of economic activity. “GDP leaves out the supply chain and business to business transactions in the production of intermediate inputs,” he notes. “That’s a big part of the economy, bigger than GDP itself. GO includes B2B activity that is vital to the production process. No one should ignore what is going on in the supply chain of the economy.”

Skousen first introduced Gross Output as a macroeconomic tool in his work The Structure of Production (New York University Press, 1990). A new third edition was published in late 2015 and is now available on Amazon.

Click here: Structure of Production on Amazon

The BEA’s decision in 2014 to publish GO on a quarterly basis in its “GDP by Industry” data is a major achievement in national income accounting. GO is the first output statistic to be published on a quarterly basis since GDP was invented in the 1940s.

The BEA now defines GDP in terms of GO. GDP is defined as “the value of the goods and services produced by the nation’s economy [GO] less the value of the goods and services used up in production (Intermediate Inputs or II].” See definitions at https://www.bea.gov/newsreleases/industry/gdpindustry/gdpindnewsrelease.htm

With GO and GDP being produced on a timely basis, the federal government now offers a complete system of accounts. As Dale Jorgenson, Steve Landefeld, and William Nordhaus conclude in their book, A New Architecture for the U. S. National Accounts, “Gross output [GO] is the natural measure of the production sector, while net output [GDP] is appropriate as a measure of welfare. Both are required in a complete system of accounts.”

Skousen adds, “Gross Output and GDP are complementary aspects of the economy, but GO does a better job of measuring total economic activity and the business cycle, and demonstrates that business spending is more significant than consumer spending,” he says. “By using GO data, we see that consumer spending is actually only about a third of economic activity, not two-thirds that is often reported by the media. As the chart above demonstrates, business spending is in fact almost twice the size of consumer spending in the US economy.”

For More Information

This just in:  My paper, “GO Beyond GDP,” which explains what GO is all about, has been ranked the #1 most downloaded paper by the Social Science Research Network (SSRN). https://papers.ssrn.com/sol3/papers.cfm?abstract_id=5002052

The GO data released by the BEA can be found at www.bea.gov under “Quarterly GDP by Industry.” Click on interactive tables “GDP by Industry” and go to “Gross Output by Industry.” Or go to this link directly: https://apps.bea.gov/iTable/?reqid=150&step=2&isuri=1&categories=gdpxind

Mark Skousen, “Slow GO May Mean a Recession Soon” Wall Street Journal, April 4, 2024: https://www.wsj.com/articles/slow-go-may-mean-a-recession-soon-us-economy-real-gross-output-65c4f1fd?mod=commentary_article_pos3

Peter Coy, “What GDP’s Cousin Can Tell Us about the Economy,” August 7, 2023, New York Times:  https://www.nytimes.com/2023/08/07/opinion/gdp-recession-gross-output.html?searchResultPosition=1

Mark Skousen, “Recession Fears May Not Pass GO: GDP is Slumping, but There’s a Better Way to Gauge the Economy.” Wall Street Journal, August 11, 2022: Recession Fears May Not Pass GO – WSJ 

If you are not a WSJ subscriber, you can read a copy of the article on: https://www.grossoutput.com/2022/09/12/recession-fears-may-not-pass-go/

Emma Rothschild, “Where is Capital?” in Capitalism: A Journal of History and Economics 2:2 (Summer 2021), pp. 291-371.  https://muse.jhu.edu/article/798746   “Essentially an attempt to apply ideas about gross output to the economic history of the industrial revolution.”  

GO-Day podcast discussion panel hosted Mark Skousen that included Steve Forbes, Sean Flynn, Steve Hanke, and David Ranson, September 30, 2020: https://chapman.zoom.us/rec/share/KJ17YjuR_6zthmgOA5fNprv2e65F-jICOsf430bJvnu8qWzdPYPfTohPC48qRLe9.Q8rmnlXynnTN74Tv?startTime=1601488807000

Steve Forbes: What’s Ahead podcast. In this podcast, Steve Forbes discusses Gross Output with Mark Skousen on September 9, 2019; he compared GDP to an X-ray of the economy, and GO to a CAT-scan: :  https://www.forbes.com/sites/steveforbes/2019/09/09/were-using-the-wrong-measure-gdp-to-gauge-the-economys-real-health-mark-skousen/#35ff3d9a52fa


For more information on Gross Output (GO), the Skousen B2B Index, and their relationship to GDP, see the following:

Mark Skousen, “If GDP Lags, Watch the Economy Grow,” Wall Street Journal, April 24, 2018:  https://www.grossoutput.com/2018/04/26/away-go-economy-growing-faster-expected/

Mark Skousen, “At Last, a Better Way to Economic Measure” lead editorial, Wall Street Journal, April 23, 2014: http://on.wsj.com/PsdoLM

Steve Forbes, Forbes Magazine (April 14, 2014): “New, Revolutionary Way To Measure The Economy Is Coming — Believe Me, This Is A Big Deal”: http://www.forbes.com/sites/steveforbes/2014/03/26/this-may-save-the-economoy-from-keynesians-and-spend-happy-pols/

Mark Skousen, Forbes Magazine (December 16, 2013): “Beyond GDP: Get Ready For A New Way To Measure The Economy”: http://www.forbes.com/sites/realspin/2013/11/29/beyond-gdp-get-ready-for-a-new-way-to-measure-the-economy/

Steve Hanke, Globe Asia (July 2014): “GO: J. M. Keynes Versus J.-B. Say,” http://www.cato.org/publications/commentary/go-jm-keynes-versus-j-b-say

David Ranson, “Output growth data that the economy generates months earlier than GDP,” Economy Watch, July 24, 2017. HCWE & Co. http://www.hcwe.com/guest/EW-0717.pdf

Mark Skousen, “Linking Austrian Economics to Keynesian Economics,” Journal of Private Enterprise, Winter, 2015: http://journal.apee.org/index.php?title=Parte7_Journal_of_Private_Enterprise_vol_30_no_4.pdf

To interview Dr. Mark Skousen on this press release, contact him at [email protected], or Ned Piplovic, Media Relations at [email protected].

# # #

________________________________________

[1] The BEA currently uses a limited measure of total sales of goods and services in the production process. Once products are fabricated and packaged at the manufacturing stage, the BEA’s GO only adds “net” sales at the wholesale and retail level. Its official GO for the first quarter of 2025 is slightly more than $52 trillion. By including gross sales at the wholesale and retail level, the Adjusted GO (GO*) expands to nearly $62.8 trillion in Q1 2025. Thus, the BEA omits almost $11 trillion in business-to-business (B2B) transactions in its GO statistics. We include them as a legitimate economic activity that should be accounted for in GO, which we call Adjusted GO. See the new introduction to Mark Skousen, The Structure of Production, 3rd ed. (New York University Press, 2015), pp. xv-xvi.

Filed Under: Articles, Featured Story, Main

FreedomFest 2025 – Day Two

June 15, 2025 By Ned Piplovic Leave a Comment

FreedomFest
Dear FreedomFest Attendee,
What an amazing start to FreedomFest yesterday! As FreedomFest continues this week, the forecast calls for lower temperatures, so things are just going to keep getting better and better here in Palm Springs! Now, it’s onto the first FULL day of programming and exhibit hall opening hours!

ARRIVING TODAY?

Thursday Registration Hours: 8:00 am – 5:00 pm

Registration Desk Location: Lobby of Palm Springs Convention Center, just inside the west entrance off of Calle Alvarado.

Parking at the convention center is free (no overnight parking) — we recommend using the west parking lot because the east doors will be locked. (So be careful when exiting the building that you don’t get locked out accidentally!)

WHERE’S THE AGENDA?
To keep the agenda as accurate as possible with any new changes, we’ve gone completely digital. Well, almost completely! We will have simple black-and-white printed copies of the daily schedule available for pickup at the registration desk.

The best way to see what’s on the schedule is to download the “Sched” app and search for “FreedomFest 2025” within the app. You can also view the agenda online.

MORNING SESSIONS
Early riser? At 7:00 am each day, join Lauren Williams on the Renaissance pool deck for Morning Yoga! (Pro tip: Wear your yoga outfit over a bathing suit so you can jump in the pool after yoga!) Then, join us for a light continental breakfast in the exhibit hall starting at 8:00 am.

Anthem movies — included in your FreedomFest pass — are available all day long in Smoketree C/D/E.

Grab a coffee and enjoy a movie every morning at 8:30 am before the general session begins.

Join Kennedy on the main stage this morning starting at 9:30 am for general sessions starring Bret Weinstein, Ryan Holiday, and more.

WHITE MATES IN TWO
In “Galt’s Gulch” (the attendee lounge inside the Exhibit Hall), try your skill at the “White Mates in Two” chess challenge provided each day. The first to solve it wins an American silver dollar! (But you have to track down Mark Skousen to receive your award!)

And don’t forget about the Selfie Contest! Post your FreedomFest selfies on social media (X, Facebook, Instagram) with @thefreedomfest and #ffest25 to enter the contest. The winner of the best selfie will win two FREE tickets to FreedomFest 2026!

EXHIBIT HALL UPDATES
Today’s book signings feature Steve Forbes, Marc Eliot, Leonard E. Reed Book Award winner Art Laffer, Twila Brase, and many other incredible authors. If you don’t have their books yet, scan the QR code at the FreedomFest Bookstore to order your copy. The author will sign an official book plate that you can adhere to the inside page of your book when you arrive home!

Tour the exhibit hall with Valerie Durham at 1:00 pm!

WHERE ARE TODAY’S LUNCHEONS AND RECEPTIONS?
With this year’s extended lunch break from 11:35 to 1:00 pm, you have more time to network, meet with exhibitors, catch an Anthem film, or even take a refreshing dip in the pool!

Arrive on time! If you have a ticket to a VIP luncheon, bear in mind that at 11:55, we fill available seats with attendees who have been on the waitlist.

  • The Stoic Feast: A Q&A Luncheon with Ryan Holiday on Mastering Life’s Challenges | 11:45 am | Primrose C (ticket required)
  • DonorsTrust Clients & Friends Luncheon | 11:45 am | Primrose D (by invitation only – visit booth #421 before lunch!)
  • Concession Snack & Lunch Kiosk | 10:00 am – 2:00 pm (lunch starts at 11:00 am) | Exhibit Hall
    • Pro Tip: Pick up a snack, sandwich, wrap, salad, or rice bowl and bring it into the Anthem Theater to watch “The Reformers” with a post-panel discussion with Bret Einstein and James Lindsay!

AFTERNOON SESSIONS
Breakout sessions are the perfect opportunity to “choose your own adventure.” If you’re attending with another person, consider splitting up and exchanging notes on multiple sessions.

Want to learn the best investment strategies?
Attend the Global Financial Summit in Primrose A.

Live Performance! For the first time ever, Anthem Film Festival is bringing you a live staged performance of Vaclav Havel’s remarkable one-act play “Protest,” during the coffee break at 3:00.

Today’s afternoon general session kicks off with the Global Economic Summit’s “Tariff-ying” Debate: Trade Wars, Protectionism, and the Future of Global Markets,” and ends with the return of the FreedomFest Mock Trial, where twelve attendee jurors will deliver the verdict on Big Pharma. Sparks will fly!

FREEDOMFEST AFTER DARK
We have planned a variety of paid and free activities this evening! Plus, Palm Canyon Drive — Palm Springs’ “Main Street” will open up to pedestrians only for their Thursday Night Street Festival from 7:00 to 10:00 pm. Enjoy your night out!

  • Anthem Filmmakers Reception & Master Class | 6:15 pm | Sierra (ticket required for non-filmmakers)
  • Anthem Movie: “Motherland” starring Holland Taylor | Smoketree C/D/E | 8:00 pm
  • Cigar Reception with Perfect Money Foundation and Brothers Solutions & Imports | 8:00 pm | Boulders Terrace (open to all!)
  • Conversation Circle – Resolved: Our Political Parties are Obsolete Institutions | 8:00 pm | Ventura (sponsored by Braver Angels)
  • Conversation Circle – Are You Religious or Spiritual? A Conversation on the Relevance of Religion Today with Daniel Kennedy of Basic Bible Guide | 8:00 pm | Mesquite C
  • Karaoke | 9:00 pm – midnight | Hotel ZOSO lobby bar – Join Avens O’Brien and the FreedomFest karaoke crew!

THE PREMIUM INVESTMENT TRAINING WORKSHOP IS TOMORROW MORNING!
Did you get your ticket yet? Tomorrow at 8:00 am, enjoy breakfast during Eagle Publishing’s session “The Power of Scalping: Learn How We Have a 91.4% Winning Track Record Trading SPY Options,” where you will learn invaluable day trading skills from Hugh Grossman and Jon Johnson. Visit the Eagle booth #320, the registration desk, or your online registration to purchase a ticket to this special session. 

SATURDAY NIGHT BANQUET & PARTY
The last night of FreedomFest is always an uproarious affair with dinner, drinks, dancing, and more!

  • Pose for the “paparazzi” on the red carpet
  • Cheer on Anthem’s grand prize winners
  • Meet “Frank Sinatra”… then share a romantic dance with your partner while he serenades you
  • Celebrate Lyn Ulbricht winning the Freedom Award
  • Be dazzled by Doc Dixon and his “assistant” Kennedy’s magic show
  • Dance the night away to classic pop/rock music provided by Triple AXL!

Visit the registration desk or modify your registration to purchase your ticket to this can’t-miss event!

POOL DAY ESCAPE & CABANA SOCIAL

Enjoy a pool day escape with the FreedomFest staff at the Palm Springs Surf Club Sunday from 10:00 am to 6:00 pm! Access to the surf club, which includes lounge chairs, large pool, lazy river, three water slides, and access to three restaurants and bars, is only $20 with your FreedomFest badge!

Upgrade your pass to include Ladies of Liberty Alliance’s exclusive cabana social by making a donation to the nonprofit. Top tier donations include bottomless mimosas, appetizers, dessert, private dip pool, and more. Cabana space is limited, so don’t delay!

Towels are available for purchase at the surf club. We recommend bringing your own if you can!

In liberty,
Valerie Durham
President & CEO
FreedomFest Palm Springs
“Oasis of Liberty”
Palm Springs Convention Center, California
June 11-14, 2025
www.freedomfest.com

Filed Under: Articles, Featured Story, Main

Business Spending Flat to Close 2024, Economic Outlook Uncertain for 2025

March 27, 2025 By Ned Piplovic Leave a Comment

  Gross Output

“By integrating the vital role of the supply chain into national income accounting, Mark Skousen’s development of gross output (GO) has created a more dynamic and broader view of the economy, and of the central role that business plays in national income, the business cycle and economic growth. I recommend that economists seriously consider his new approach to macroeconomics.”

– Finn Kydland, Professor of Economics, University of California at Santa Barbara, 2004 Nobel prize winner

“It’s at least conceivable that gross output is a leading indicator of the economy.”

– Peter Coy, Economics Editor, New York Times (Aug 7, 2023)


Washington, DC (Thursday, March 27, 2024):

Today the federal government (BEA) released 4th quarter gross output (GO), the top-line that measures spending at all stages of production. Adjusted real gross output (GO*)[1]

increased 1.9%. While delivering a positive result, the growth was substantially lower that the 3.0% expansion from the previous period. Real GDP outpaced GO* growth in the fourth quarter and expanded 2.4%. The GO trailing GDP growth indicates potential economic weakness. The main concern is the fourth-quarter Business (B2B) spending, which increased only 0.6% in real terms – after rising 2.9% in the preceding period.
While lower than the third-quarter growth rate of 3.0%, the 1.9% adjusted GO (GO*) increase in Q4 is still notably higher than the 1.2% average growth rate over the three periods ending in Q2 2024. Furthermore, after trailing GO in the first three quarters of 2024, the Adjusted GO grew at a higher rate in Q4. This generally indicates economic expansion ahead. It is important to note that half of the Q4 activity occurred before we knew the results of the presidential election in November. Therefore, some of the slowdown in business spending could have been triggered by concerns over the election outcome, and the direction of future economic policies depending on which party won control of the executive branch. However, even with the new – presumably pro-business administration – some concerns still linger. The main apprehension relates to the new administration’s intent to implement tariffs on importation of goods even from our closest economic ally’s, such as Canada, Mexico and the EU.
The current data for Q4 2025 sends mixed signals. The Adjusted GO growth rate has risen above the GO growth rate, which generally indicates steady expansion of the economy in the few upcoming quarters. Furthermore, the current fourth quarter growth is in line with the 2% fourth-quarter growth in 2023 and ahead of the 0.4% contraction in 2022.

Alternatively, both GO and GO* growth rates are slightly below the GDP growth rate, which could indicate a leveling off in the economy, and even a possible tightening. Businesses were cautious about spending over the past four periods. Additionally, real-term business spending (B2B) seems to decline in the last quarter of the year, which is not surprising in any given year because businesses frequently pull back on Q4 expenditures based on year-to-date results to meet their year-end budgets. As indicated above, this last-quarter spending pullback effect might be amplified by the uncertainty of an election year as we experienced in 2024. The GDP figures – which are dominated by consumer spending – show expansion almost always and overestimate the health of the economy. However, business spending is more sensitive to the ups and down of the economy, which makes it a better indicator of the direction that the economy might take in the near future.
The Federal Reserve did not anticipate a major economic downturn. Therefore, it has kept the interest at the 4.25%-4.50% range at their March 19, 2025 meeting. However, the Fed indicated the possibility of two quarter-percentage-point cuts in 2025 in case they notice any weakness in the economy for the rest of the year.

While the Trump administration made some small steps in discussions about a potential ceasefire with Volodymyr Zelenskyy and Vladimir Putin, a lasting peace agreement regarding the Ukraine war is not in sight yet. A permanent solution to this conflict would contribute significantly towards easing fears and incentivizing economic expansion in Europe and Asia. However, even the small steps achieved already are easing tensions and are instilling confidence that at least we should not see a major downturn of the U.S. economy.

Unlike consumption, which maintains a steady uptrend over the long term, business spending is significantly more volatile and more sensitive to economic fluctuations. Therefore, the slowly increasing business spending growth over the past several quarters, could indicate also that we might be safe from a recession, and on the way towards a steady economic expansion.

[1] The BEA currently uses a limited measure of total sales of goods and services in the production process. Once products are fabricated and packaged at the manufacturing stage, the BEA’s GO only adds “net” sales at the wholesale and retail level. Its official GO for the fourth quarter of 2024 is slightly less than $51.5 trillion. By including gross sales at the wholesale and retail level, the Adjusted GO (GO*) expands to nearly $62.4 trillion in Q4 2024. Thus, the BEA omits almost $11 trillion in business-to-business (B2B) transactions in its GO statistics. We include them as a legitimate economic activity that should be accounted for in GO, which we call Adjusted GO. See the new introduction to Mark Skousen, The Structure of Production, 3rd ed. (New York University Press, 2015), pp. xv-xvi.


Gross Output


GO as a Leading Indicator

In our model, GO – which includes the value of the supply chain – is a leading indicator of where the economy is headed in the year. When GO grows faster than GDP, it suggests economic expansion over the next few quarters, and vice versa. Currently, the BEA’s real GO* growth rate of 1.9% is slightly lower than the annualized GDP growth rate of 2.4%. The static view might indicate that the economy is facing headwinds entering 2025. However, the fourth quarter metrics do not paint a clear picture.


Gross Output


After four quarters of mixed signals regarding the direction of the economy in the near term, the mixed economic data for the fourth quarter did not give any clearer indication regarding the long-term economic growth outlook. The first-quarter 2025 GO data is scheduled to be released in late June, which will hopefully give a clearer indication of the economic direction for the rest of 2025.

Just as close as in real terms, fourth-quarter 2024 nominal growth rates were even closer, with GDP expanding 4.8% to reach $29.7 trillion and GO rising 4.4% to exceed $51 trillion for the first time ever.

The Adjusted GO – which includes the gross wholesale and gross retail figures (included only as net figures in the GO reported by the BEA) – advanced 4.6% in nominal terms at the end of the fourth-quarter 2024 and has also reached a new milestone by rising above $61 trillion for the first time. The difference between net and gross figures amounts to nearly $11 trillion, which is missing from the government’s official GO figure, but we include it in our Adjusted GO measure.

Our GO model has proven reliably accurate in projecting the direction of GDP under normal economic circumstances.

The Importance of GO

Most economists are still unaware of the value of GO and use only GDP when gauging economic outlook. However, gross output (GO) should be viewed as the top line in national income accounting, and GDP is the bottom line. Both metrics are essential to understanding where the economy is headed.

As Dale Jorgenson, Steve Landefeld, and William Nordhaus conclude in their book, A New Architecture for the U. S. National Accounts, “Gross output [GO] is the natural measure of the production sector, while net output [GDP] is appropriate as a measure of welfare. Both are required in a complete system of accounts.”

As Steve Forbes has suggested, “GDP is the X-ray of the economy; GO is the CAT-scan.”

Business – Not Consumers – Drives the Economy

Another benefit of GO is that it dispels the myth that consumer spending drives the economy. Contrary to views of many academic economists and wide-spread media reports, consumer spending does not represent two-thirds of total economic activity. Using GO as a better and a more accurate measure of total spending in the economy, the business sector (B2B spending) is almost twice the size of consumer spending. Consumer spending is the effect, not the cause, of prosperity (Say’s law).


Gross Output


Therefore, our business-to-business (B2B) index is very useful for assessing the underlying health of the overall economy and its potential to bounce back after economic declines. The B2B Index measures all the business spending in the supply chain and new private capital investment. After expanding at an average rate of nearly 4% over the first three quarters in 2024, the nominal B2B growth slowed to just 2.9% in Q4 2024, which pushed the annualized B2B spending to a new high of more than $35 trillion. At the same time, consumer spending expanded 6.5% – approximately a whole percentage point higher than the average growth in the first three quarters of 2024 – and also reached a new high by cracking the $20 trillion mark. In real terms, business spending grew 0.6% on an annualized basis, and consumer spending expanded 0.9%

“B2B spending is in fact a pretty good indicator of where the economy is headed, since it is more responsive to the boom-bust economic cycle than consumer spending,” states Mark Skousen, editor of Forecasts & Strategies and the Doti-Spogli Chair of Free Enterprise at Chapman University.

While GDP includes only a small portion of investment spending, GO accounts for significantly more of the business investment outlays, which tend to indicate economic direction over extended periods. As David Ranson, chief economist for the private forecasting firm HCWE & Co., states, “Movements in gross output serve as a leading indicator of movements in GDP.”

The federal government will release the advance estimate for first-quarter 2025 GDP on April 30, 2025. The full release of Q1 Gross Output data, as well as the third estimate of GDP are scheduled for June 26, 2025.

Important Note:  We are hopeful that in the near future, the BEA will release GO at the same time as the first estimate of GDP for the quarter, not the third estimate. We also recommend that GO be elevated in the BEA’s press releases and website as the “top line” in national income accounting, since GO data often tells a very different story than GDP data.

Report on Various Sectors of the Economy

Despite a moderate expansion of the overall economy, one of the major economic sectors experienced a pullback again in Q4 2024 as it did in the past three periods.

However, sectors in the very early stages of production expanded slightly, which could indicate an economic expansion down the line, as these sectors generally are better early indicators of economic direction than later stages of production.
After declining for five consecutive quarters in real terms, the Agriculture sector delivered a marginal expansion of 0.3%. Furthermore, the Mining sector reversed a 1.9% decline from Q3 and grew 0.8% in the last period of the year. The Utilities segment added to the positive result by reversing its own third quarter contraction of 2.6% into a 0.6% expansion in Q4 2024.

While these three sectors account for less than 4% of the overall economy, they are all early-stage sectors, which can signal how the later stages and the overall economy might shift over the subsequent few periods.

The Construction sector, which accounts for more than 4% of the economy expanded 3.7%. The major sector that contracted was the Manufacturing sector. The second-largest sector with a 14% share of the overall economy, reversed a small gain of 1.5% from Q3, and contracted 0.9% in the fourth quarter. Furthermore, while nondurable goods still expanded (1.4%), manufacturing of durable goods – which has a larger implication on indicating the long-term direction of the economy – contracted 3.1%.

While the Wholesale trade grew nearly 2% and the Retail expanded 6.4%, the Transportation and Warehousing sector advanced 6.1%, Additionally, when compared to the 7.9% growth in the third quarter, the Information sector increase was relatively flat with a 1% expansion.

After delivering a flat performance in the previous period, the largest segment that accounts for nearly a fifth of the overall economy – Finance, insurance, real estate, rental, and leasing – delivered another similar performance with a 0.3% growth. The main driver of this performance was a 3.2% contraction of the Finance and insurance subsegment.

Three late-stage sectors – Professional and business services; Educational services, health care, and social assistance; and Arts, entertainment, recreation, accommodation, and food services, which account combined for more than a fourth of the overall economy – expanded 1.8%, 3.2%, and 3.8% respectively.

Another drag on the economy is the expansion of government spending for the third consecutive period at similar growth rates. Overall government spending increases 3.1% in Q4 2024. In past periods we saw imbalanced growth where one level of government grew more than the other. However, in the most recent period at the end of 2024, the growth rates were nearly identical with Federal government expanding 3.2%, and State and local governments growing at a marginally lower rate of 3.0% from Q3 to Q4 2024.

Gross output (GO) and GDP are complementary statistics in national income accounting. GO is an attempt to measure the “make” economy; i.e., total economic activity at all stages of production, similar to the “top line” (revenues/sales) of a financial accounting statement. In April 2014, the BEA began to measure GO on a quarterly basis along with GDP.

Gross domestic product (GDP) is an attempt to measure the “use” economy, i.e., the value of finished goods and services ready to be used by consumers, business and government. GDP is not quite the same as the “bottom line” (profit, or net income) of an accounting statement, but rather the “value added” or the value of final use.
GO tends to be more sensitive to the business cycle, and more volatile, than GDP.

About GO and B2B Index

Skousen champions Gross Output as a more comprehensive measure of economic activity. “GDP leaves out the supply chain and business to business transactions in the production of intermediate inputs,” he notes. “That’s a big part of the economy, bigger than GDP itself. GO includes B2B activity that is vital to the production process. No one should ignore what is going on in the supply chain of the economy.”

Skousen first introduced Gross Output as a macroeconomic tool in his work The Structure of Production (New York University Press, 1990). A new third edition was published in late 2015 and is now available on Amazon.

Click here: Structure of Production on Amazon

The BEA’s decision in 2014 to publish GO on a quarterly basis in its “GDP by Industry” data is a major achievement in national income accounting. GO is the first output statistic to be published on a quarterly basis since GDP was invented in the 1940s.

The BEA now defines GDP in terms of GO. GDP is defined as “the value of the goods and services produced by the nation’s economy [GO] less the value of the goods and services used up in production (Intermediate Inputs or II].” See definitions at https://www.bea.gov/newsreleases/industry/gdpindustry/gdpindnewsrelease.htm

With GO and GDP being produced on a timely basis, the federal government now offers a complete system of accounts. As Dale Jorgenson, Steve Landefeld, and William Nordhaus conclude in their book, A New Architecture for the U. S. National Accounts, “Gross output [GO] is the natural measure of the production sector, while net output [GDP] is appropriate as a measure of welfare. Both are required in a complete system of accounts.”

Skousen adds, “Gross Output and GDP are complementary aspects of the economy, but GO does a better job of measuring total economic activity and the business cycle, and demonstrates that business spending is more significant than consumer spending,” he says. “By using GO data, we see that consumer spending is actually only about a third of economic activity, not two-thirds that is often reported by the media. As the chart above demonstrates, business spending is in fact almost twice the size of consumer spending in the US economy.”

For More Information

This just in:  My paper, “GO Beyond GDP,” which explains what GO is all about, has been ranked the #1 most downloaded paper by the Social Science Research Network (SSRN). https://papers.ssrn.com/sol3/papers.cfm?abstract_id=5002052

The GO data released by the BEA can be found at www.bea.gov under “Quarterly GDP by Industry.” Click on interactive tables “GDP by Industry” and go to “Gross Output by Industry.” Or go to this link directly: https://apps.bea.gov/iTable/?reqid=150&step=2&isuri=1&categories=gdpxind

Mark Skousen, “Slow GO May Mean a Recession Soon” Wall Street Journal, April 4, 2024: https://www.wsj.com/articles/slow-go-may-mean-a-recession-soon-us-economy-real-gross-output-65c4f1fd?mod=commentary_article_pos3

Peter Coy, “What GDP’s Cousin Can Tell Us about the Economy,” August 7, 2023, New York Times:  https://www.nytimes.com/2023/08/07/opinion/gdp-recession-gross-output.html?searchResultPosition=1

Mark Skousen, “Recession Fears May Not Pass GO: GDP is Slumping, but There’s a Better Way to Gauge the Economy.” Wall Street Journal, August 11, 2022: Recession Fears May Not Pass GO – WSJ 

If you are not a WSJ subscriber, you can read a copy of the article on: https://www.grossoutput.com/2022/09/12/recession-fears-may-not-pass-go/

Emma Rothschild, “Where is Capital?” in Capitalism: A Journal of History and Economics 2:2 (Summer 2021), pp. 291-371.  https://muse.jhu.edu/article/798746   “Essentially an attempt to apply ideas about gross output to the economic history of the industrial revolution.”  

GO-Day podcast discussion panel hosted Mark Skousen that included Steve Forbes, Sean Flynn, Steve Hanke, and David Ranson, September 30, 2020: https://chapman.zoom.us/rec/share/KJ17YjuR_6zthmgOA5fNprv2e65F-jICOsf430bJvnu8qWzdPYPfTohPC48qRLe9.Q8rmnlXynnTN74Tv?startTime=1601488807000

Steve Forbes: What’s Ahead podcast. In this podcast, Steve Forbes discusses Gross Output with Mark Skousen on September 9, 2019; he compared GDP to an X-ray of the economy, and GO to a CAT-scan: :  https://www.forbes.com/sites/steveforbes/2019/09/09/were-using-the-wrong-measure-gdp-to-gauge-the-economys-real-health-mark-skousen/#35ff3d9a52fa


For more information on Gross Output (GO), the Skousen B2B Index, and their relationship to GDP, see the following:

Mark Skousen, “If GDP Lags, Watch the Economy Grow,” Wall Street Journal, April 24, 2018:  https://www.grossoutput.com/2018/04/26/away-go-economy-growing-faster-expected/

Mark Skousen, “At Last, a Better Way to Economic Measure” lead editorial, Wall Street Journal, April 23, 2014: http://on.wsj.com/PsdoLM

Steve Forbes, Forbes Magazine (April 14, 2014): “New, Revolutionary Way To Measure The Economy Is Coming — Believe Me, This Is A Big Deal”: http://www.forbes.com/sites/steveforbes/2014/03/26/this-may-save-the-economoy-from-keynesians-and-spend-happy-pols/

Mark Skousen, Forbes Magazine (December 16, 2013): “Beyond GDP: Get Ready For A New Way To Measure The Economy”: http://www.forbes.com/sites/realspin/2013/11/29/beyond-gdp-get-ready-for-a-new-way-to-measure-the-economy/

Steve Hanke, Globe Asia (July 2014): “GO: J. M. Keynes Versus J.-B. Say,” http://www.cato.org/publications/commentary/go-jm-keynes-versus-j-b-say

David Ranson, “Output growth data that the economy generates months earlier than GDP,” Economy Watch, July 24, 2017. HCWE & Co. http://www.hcwe.com/guest/EW-0717.pdf

Mark Skousen, “Linking Austrian Economics to Keynesian Economics,” Journal of Private Enterprise, Winter, 2015: http://journal.apee.org/index.php?title=Parte7_Journal_of_Private_Enterprise_vol_30_no_4.pdf

To interview Dr. Mark Skousen on this press release, contact him at [email protected], or Ned Piplovic, Media Relations at [email protected].

# # #

________________________________________

[1] The BEA currently uses a limited measure of total sales of goods and services in the production process. Once products are fabricated and packaged at the manufacturing stage, the BEA’s GO only adds “net” sales at the wholesale and retail level. Its official GO for the third quarter of 2024 is slightly less than $51 trillion. By including gross sales at the wholesale and retail level, the Adjusted GO (GO*) expands to nearly $61 trillion in Q3 2024. Thus, the BEA omits almost $11 trillion in business-to-business (B2B) transactions in its GO statistics. We include them as a legitimate economic activity that should be accounted for in GO, which we call Adjusted GO. See the new introduction to Mark Skousen, The Structure of Production, 3rd ed. (New York University Press, 2015), pp. xv-xvi.

Filed Under: Articles, Featured Story, Main

Business Spending Rebounds, Recession Avoided

December 19, 2024 By Ned Piplovic 1 Comment

  Gross Output

“By integrating the vital role of the supply chain into national income accounting, Mark Skousen’s development of gross output (GO) has created a more dynamic and broader view of the economy, and of the central role that business plays in national income, the business cycle and economic growth. I recommend that economists seriously consider his new approach to macroeconomics.”

– Finn Kydland, Professor of Economics, University of California at Santa Barbara, 2004 Nobel prize winner

“It’s at least conceivable that gross output is a leading indicator of the economy.”

– Peter Coy, Economics Editor, New York Times (Aug 7, 2023)


Washington, DC (Thursday, December 19, 2024):

Today the federal government (BEA) released 3rd quarter gross output (GO), the top-line that measures spending at all stages of production.  Real GO rose 3.1%, a substantial improvement from previous quarters, and equal to real GDP for the third quarter. This is good news. Assuming the fourth quarter GO is positive, it looks like the US avoided a recession in 2024.  Business (B2B) spending also rose 2.9%.

After increasing an average 1.2% over the preceding three quarters, the Adjusted GO (GO*)[1] – which measures spending at all stages of production – delivered a significant bump and rose 3.0% in real terms for the third quarter of 2024. For the third consecutive period the Adjusted GO growth trailed GO growth rates published by the BEA, but the gap has narrowed significantly. This is indicating that the business spending is increasing comparing to previous few periods, and signals that fears of recession from earlier in the year are dissipating quickly. It is important to keep in mind that these are third-quarter results – before we knew the results of the presidential election. With the new pro-business administration set to take office next month, and already courting heads of mayor domestic and international businesses to set growth strategies, we might see a brisk increase in business investment spending as early as the last quarter of 2024 – for which the data will be released in March 2025.

The continuously increasing growth rate of BEA’s GO numbers indicates that the economy should most likely avoid a recession and that it might be set for a strong positive growth in the next year, barring any unforeseen, black swan-type events. The one piece of the puzzle still needed for absolute confirmation of the strong economic growth to come is that the adjusted real GO (GO*) growth rate rises above the GO growth rate. The Adjusted GO has been increasing steadily over the past few quarters and its growth rate might be back above the GO growth rate as early as the fourth quarter, thus confirming the optimistic outlook for an expanding economy in 2025. 

Businesses were cautious about spending over the past four periods. However, real-term business spending (B2B) has been ramping up lately. This is a continuing indication that the business sector – which is substantially larger than the retail sector and generally has a better view of the direction of the economy than the consumers – is becoming more confident that a faster economic expansion is in the near-term future. The GDP figures – which are dominated by consumer spending – show expansion almost always and overestimate the health of the economy.  However, business spending is more sensitive to the ups and down of the economy, which makes it a better indicator of the direction that the economy might take in the near future.

While business spending is probably the most significant indicator, economic outlook hinges on several additional factors. The uncertainty of the U.S. presidential election is now behind us. Whether you see the results of the U.S. presidential election as good, bad or indifferent, at least the uncertainty is over, which makes other factors easier considerations. Domestically, the Federal Reserve cut interest rates yesterday to a 4.25%-4.50% range, but projects only two more quarter-percentage-point cuts in 2025.

Continued concerns of the war in Ukraine are still high on the international stage. However, hopes are that the new administration in the Executive branch might be able to broker some kind of ceasefire, or permanent solution to the conflict. While permanent solution is preferable, even a minor improvement in this conflict would go a long way into easing further trepidations about economic conditions in Europe and Asia, which are easing already on the prospect of the U.S. economic expansion. One concern that could derail U.S. economic growth are president-elect’s threats to implement wide-ranging tariffs on imports from our economic rivals like China, as well as our economic partners like Canada. Unlike consumption, which maintains a steady uptrend over the long term, business spending is significantly more volatile and more sensitive to economic fluctuations. Therefore, the slowly increasing business spending growth over the past several quarters, could indicate that we might be safe from a recession, and on the way towards a significant economic expansion.

[1] The BEA currently uses a limited measure of total sales of goods and services in the production process. Once products are fabricated and packaged at the manufacturing stage, the BEA’s GO only adds “net” sales at the wholesale and retail level. Its official GO for the third quarter of 2024 is slightly less than $51 trillion. By including gross sales at the wholesale and retail level, the Adjusted GO (GO*) expands to nearly $61 trillion in Q3 2024. Thus, the BEA omits almost $11 trillion in business-to-business (B2B) transactions in its GO statistics. We include them as a legitimate economic activity that should be accounted for in GO, which we call Adjusted GO. See the new introduction to Mark Skousen, The Structure of Production, 3rd ed. (New York University Press, 2015), pp. xv-xvi.

Gross Output


GO as a Leading Indicator

In our model, GO – which includes the value of the supply chain – is a leading indicator of where the economy is headed in the year. When GO grows faster than GDP, it suggests economic expansion over the next few quarters, and vice versa. Currently, the BEA’s real GO’s Q2 real growth rate of 3.2% is slightly higher than the annualized GDP growth rate of 3.1%. The static view of the nearly identical growth rates does not offer any insights about the direction of the economy. However, the dynamic view of the GO growth rate rising faster than GDP growth rate indicates that the recession fears have subsided and that the outlook on economic growth has shifted to positive going into 2025.

Gross Output


After four quarters of mixed signals regarding the direction of the economy in the near term, economic data for the third quarter indicates a positive shift in the economic growth outlook as we head towards 2025. The fourth-quarter and 2024 full-year GO data is scheduled to be released in late March next year, which will hopefully confirm the uptrend and help in signaling the economy’s path for the rest of 2025.

Just as close as in real terms, third-quarter 2024 nominal growth rates were similarly equal, with GDP expanding 5.0% to exceed $29.4 trillion and GO rising 5.2% to $50.3 trillion.

The Adjusted GO – which includes the gross wholesale and gross retail figures (included only as net figures in the GO reported by the BEA) – advanced 5.0% in nominal terms at the end of the third quarter 2024 and is now slightly over of $60.7 trillion. The difference between net and gross figures amounts to nearly $11 trillion, which is missing from the government’s official GO figure, but we include it in our Adjusted GO measure.

Our GO model has proven reliably accurate in projecting the direction of GDP under normal economic circumstances.

The Importance of GO

Most economists are still unaware of the value of GO and use only GDP when gauging economic outlook. However, gross output (GO) should be viewed as the top line in national income accounting, and GDP is the bottom line. Both metrics are essential to understanding where the economy is headed.

As Dale Jorgenson, Steve Landefeld, and William Nordhaus conclude in their book, A New Architecture for the U. S. National Accounts, “Gross output [GO] is the natural measure of the production sector, while net output [GDP] is appropriate as a measure of welfare. Both are required in a complete system of accounts.”

As Steve Forbes has suggested, “GDP is the X-ray of the economy; GO is the CAT-scan.” 

Business – Not Consumers – Drives the Economy

Another benefit of GO is that it dispels the myth that consumer spending drives the economy. Contrary to views of many academic economists and wide-spread media reports, consumer spending does not represent two-thirds of total economic activity. Using GO as a better and a more accurate measure of total spending in the economy, the business sector (B2B spending) is almost twice the size of consumer spending. Consumer spending is the effect, not the cause, of prosperity (Say’s law).

Gross Output

Therefore, our business-to-business (B2B) index is very useful for assessing the underlying health of the overall economy and its potential to bounce back after economic declines. The B2B Index measures all the business spending in the supply chain and new private capital investment. After expanding 3.0% and 3.6% in the previous two periods, nominal B2B delivered a 4.9% increase in Q3 2024, which pushed the annualized B2B spending to more than $34.8 trillion. At the same time, consumer spending expanded 5.3% – relatively flat to previous period – and currently stands just short of $20 trillion. In real terms, business spending grew 2.9%, and consumer spending expanded 3.3% 

“B2B spending is in fact a pretty good indicator of where the economy is headed, since it is more responsive to the boom-bust economic cycle than consumer spending,” states Mark Skousen, editor of Forecasts & Strategies and the Doti-Spogli Chair of Free Enterprise at Chapman University.

While GDP includes only a small portion of investment spending, GO accounts for significantly more of the business investment outlays, which tend to indicate economic direction over extended periods. As David Ranson, chief economist for the private forecasting firm HCWE & Co., states, “Movements in gross output serve as a leading indicator of movements in GDP.”

The federal government will release the advance estimate for fourth-quarter and 2024 full-year GDP on January 30, 2025. The full release of Q4 Gross Output data, as well as the third estimate of GDP are scheduled for March 27, 2025..

Important Note:  We are hopeful that in the near future, the BEA will release GO at the same time as the first estimate of GDP for the quarter, not the third estimate. We also recommend that GO be elevated in the BEA’s press releases and website as the “top line” in national income accounting, since GO data often tells a very different story than GDP data.

Report on Various Sectors of the Economy

Despite the robust expansion of the overall economy, three of the major economic sectors experienced a pullback again in Q3 2024 as they did in the past two periods. Moreover, because these three sectors are in the very early stages of production, they generally are better early indicators of economic direction than later stages of production. However, the contractions were relatively mild compared to past few periods, which is a slightly positive indicator for the rest of the economy going forward.

After declining more than 9% in Q2, the Agriculture sector contracted merely 4.6% in Q3. This marks the fourth consecutive quarter of contraction in real terms for the sector. The Mining sector which posted a small gain in the previous period but contracted more than 6% in Q1, declined just 1.9% in Q3. However, the Utilities segment was the biggest mover, which followed a plummet of more than 25% in Q2 with a contraction of just 2.6% in Q3 2024.

While these three sectors account for less than 4% of the overall economy, they are all early-stage sectors, which can signal how the later stages and the overall economy might shift over the subsequent few periods.

The Construction sector was flat to the previous period. As the second-largest sector with a more than 14% share of the overall economy, the Manufacturing sector reversed a contraction of 2% in the previous period and expanded 1.5% in Q3. Furthermore, this expansion was driven by a 3.5% growth in nondurable goods, which is an even better positive sign for the extended economic outlook.

While the Wholesale trade grew nearly 6% and the Retail expanded 12.3%, the Transportation and Warehousing sector advanced 4.4%, Additionally, the Information sector increased 7.9%.

The largest segment that accounts for nearly a fifth of the overall economy – Finance, insurance, real estate, rental, and leasing – expanded 0.4%, which is in line with last period’s performance.

Three late-stage sectors – Professional and business services; Educational services, health care, and social assistance; and Arts, entertainment, recreation, accommodation, and food services, which account combined for more than a fourth of the overall economy – expanded 3.3% and 6.1%, and 0.7% respectively. 

After declining for three consecutive quarters, the government spending growth rate reversed direction last period, and has again done so this period. Overall government spending followed a 2.7% expansion from the last period with a 3.6% increase in Q3 2024. The main driver behind this increase was the 7.1% increase in Federal government spending, which was just 1.3% in the previous quarter. Alternatively, State and local governments grew a slightly little slower rate, and followed a 3.1% expansion from Q2 with a 2.1% increase in Q3 2024.

Gross output (GO) and GDP are complementary statistics in national income accounting. GO is an attempt to measure the “make” economy; i.e., total economic activity at all stages of production, similar to the “top line” (revenues/sales) of a financial accounting statement. In April 2014, the BEA began to measure GO on a quarterly basis along with GDP.

Gross domestic product (GDP) is an attempt to measure the “use” economy, i.e., the value of finished goods and services ready to be used by consumers, business and government. GDP is not quite the same as the “bottom line” (profit, or net income) of an accounting statement, but rather the “value added” or the value of final use.

GO tends to be more sensitive to the business cycle, and more volatile, than GDP.

About GO and B2B Index

Skousen champions Gross Output as a more comprehensive measure of economic activity. “GDP leaves out the supply chain and business to business transactions in the production of intermediate inputs,” he notes. “That’s a big part of the economy, bigger than GDP itself. GO includes B2B activity that is vital to the production process. No one should ignore what is going on in the supply chain of the economy.”

Skousen first introduced Gross Output as a macroeconomic tool in his work The Structure of Production (New York University Press, 1990). A new third edition was published in late 2015 and is now available on Amazon.

Click here: Structure of Production on Amazon

The BEA’s decision in 2014 to publish GO on a quarterly basis in its “GDP by Industry” data is a major achievement in national income accounting. GO is the first output statistic to be published on a quarterly basis since GDP was invented in the 1940s.

The BEA now defines GDP in terms of GO. GDP is defined as “the value of the goods and services produced by the nation’s economy [GO] less the value of the goods and services used up in production (Intermediate Inputs or II].” See definitions at https://www.bea.gov/newsreleases/industry/gdpindustry/gdpindnewsrelease.htm

With GO and GDP being produced on a timely basis, the federal government now offers a complete system of accounts. As Dale Jorgenson, Steve Landefeld, and William Nordhaus conclude in their book, A New Architecture for the U. S. National Accounts, “Gross output [GO] is the natural measure of the production sector, while net output [GDP] is appropriate as a measure of welfare. Both are required in a complete system of accounts.”

Skousen adds, “Gross Output and GDP are complementary aspects of the economy, but GO does a better job of measuring total economic activity and the business cycle, and demonstrates that business spending is more significant than consumer spending,” he says. “By using GO data, we see that consumer spending is actually only about a third of economic activity, not two-thirds that is often reported by the media. As the chart above demonstrates, business spending is in fact almost twice the size of consumer spending in the US economy.”

For More Information

This just in:  My paper, “GO Beyond GDP,” which explains what GO is all about, has been ranked the #1 most downloaded paper by the Social Science Research Network (SSRN). https://papers.ssrn.com/sol3/papers.cfm?abstract_id=5002052

The GO data released by the BEA can be found at www.bea.gov under “Quarterly GDP by Industry.” Click on interactive tables “GDP by Industry” and go to “Gross Output by Industry.” Or go to this link directly: https://apps.bea.gov/iTable/?reqid=150&step=2&isuri=1&categories=gdpxind

Mark Skousen, “Slow GO May Mean a Recession Soon” Wall Street Journal, April 4, 2024: https://www.wsj.com/articles/slow-go-may-mean-a-recession-soon-us-economy-real-gross-output-65c4f1fd?mod=commentary_article_pos3

Peter Coy, “What GDP’s Cousin Can Tell Us about the Economy,” August 7, 2023, New York Times:  https://www.nytimes.com/2023/08/07/opinion/gdp-recession-gross-output.html?searchResultPosition=1

Mark Skousen, “Recession Fears May Not Pass GO: GDP is Slumping, but There’s a Better Way to Gauge the Economy.” Wall Street Journal, August 11, 2022: Recession Fears May Not Pass GO – WSJ 

If you are not a WSJ subscriber, you can read a copy of the article on: https://www.grossoutput.com/2022/09/12/recession-fears-may-not-pass-go/

Emma Rothschild, “Where is Capital?” in Capitalism: A Journal of History and Economics 2:2 (Summer 2021), pp. 291-371.  https://muse.jhu.edu/article/798746   “Essentially an attempt to apply ideas about gross output to the economic history of the industrial revolution.”  

GO-Day podcast discussion panel hosted Mark Skousen that included Steve Forbes, Sean Flynn, Steve Hanke, and David Ranson, September 30, 2020: https://chapman.zoom.us/rec/share/KJ17YjuR_6zthmgOA5fNprv2e65F-jICOsf430bJvnu8qWzdPYPfTohPC48qRLe9.Q8rmnlXynnTN74Tv?startTime=1601488807000

Steve Forbes: What’s Ahead podcast. In this podcast, Steve Forbes discusses Gross Output with Mark Skousen on September 9, 2019; he compared GDP to an X-ray of the economy, and GO to a CAT-scan: :  https://www.forbes.com/sites/steveforbes/2019/09/09/were-using-the-wrong-measure-gdp-to-gauge-the-economys-real-health-mark-skousen/#35ff3d9a52fa


For more information on Gross Output (GO), the Skousen B2B Index, and their relationship to GDP, see the following:

Mark Skousen, “If GDP Lags, Watch the Economy Grow,” Wall Street Journal, April 24, 2018:  https://www.grossoutput.com/2018/04/26/away-go-economy-growing-faster-expected/

Mark Skousen, “At Last, a Better Way to Economic Measure” lead editorial, Wall Street Journal, April 23, 2014: http://on.wsj.com/PsdoLM

Steve Forbes, Forbes Magazine (April 14, 2014): “New, Revolutionary Way To Measure The Economy Is Coming — Believe Me, This Is A Big Deal”: http://www.forbes.com/sites/steveforbes/2014/03/26/this-may-save-the-economoy-from-keynesians-and-spend-happy-pols/

Mark Skousen, Forbes Magazine (December 16, 2013): “Beyond GDP: Get Ready For A New Way To Measure The Economy”: http://www.forbes.com/sites/realspin/2013/11/29/beyond-gdp-get-ready-for-a-new-way-to-measure-the-economy/

Steve Hanke, Globe Asia (July 2014): “GO: J. M. Keynes Versus J.-B. Say,” http://www.cato.org/publications/commentary/go-jm-keynes-versus-j-b-say

David Ranson, “Output growth data that the economy generates months earlier than GDP,” Economy Watch, July 24, 2017. HCWE & Co. http://www.hcwe.com/guest/EW-0717.pdf

Mark Skousen, “Linking Austrian Economics to Keynesian Economics,” Journal of Private Enterprise, Winter, 2015: http://journal.apee.org/index.php?title=Parte7_Journal_of_Private_Enterprise_vol_30_no_4.pdf

To interview Dr. Mark Skousen on this press release, contact him at [email protected], or Ned Piplovic, Media Relations at [email protected].

# # #

________________________________________

[1] The BEA currently uses a limited measure of total sales of goods and services in the production process. Once products are fabricated and packaged at the manufacturing stage, the BEA’s GO only adds “net” sales at the wholesale and retail level. Its official GO for the third quarter of 2024 is slightly less than $51 trillion. By including gross sales at the wholesale and retail level, the Adjusted GO (GO*) expands to nearly $61 trillion in Q3 2024. Thus, the BEA omits almost $11 trillion in business-to-business (B2B) transactions in its GO statistics. We include them as a legitimate economic activity that should be accounted for in GO, which we call Adjusted GO. See the new introduction to Mark Skousen, The Structure of Production, 3rd ed. (New York University Press, 2015), pp. xv-xvi.

Filed Under: Articles, Featured Story, Main

Slowing Gross Output Confirms Fed’s Need to Cut Rates

September 26, 2024 By Ned Piplovic Leave a Comment

  Gross Output

“By integrating the vital role of the supply chain into national income accounting, Mark Skousen’s development of gross output (GO) has created a more dynamic and broader view of the economy, and of the central role that business plays in national income, the business cycle and economic growth. I recommend that economists seriously consider his new approach to macroeconomics.”

– Finn Kydland, Professor of Economics, University of California at Santa Barbara, 2004 Nobel prize winner

“It’s at least conceivable that gross output is a leading indicator of the economy.”

– Peter Coy, Economics Editor, New York Times (Aug 7, 2023)


Washington, DC (Thursday, September 26, 2024): The federal government (BEA) released today the figures for the second-quarter 2024 gross output (GO) – the top line in national income accounting. After increasing 1.4% in Q4 2023 and rising just 1.0% in the first quarter of 2024, the Adjusted GO (GO*)[1] – which measures spending at all stages of production – delivered lethargic growth of just 1.2% in real terms for the second quarter of 2024. Using BEA’s net figure, real GO grew 1.8%, much higher than the Adjusted Gross Output (GO*), indicating that the spending in the supply chain is lagging and which might spell troubles for the economy in the near future. This is the second consecutive period in which the Adjusted GO growth trailed GO growth rates published by the BEA.

While the BEA’s GO numbers indicate a slightly positive outlook about economic growth over the next few quarters, the lethargic growth of the adjusted real GO suggests that the economy is struggling and might turn negative as a result of any disruption. With the Boeing workers already on strike, and two more labor strikes looming – auto workers and east coast port workers – the danger of an economic downturn is substantial. 

Another reason to be cautious about economic growth is that business spending continues to underperform compared to consumer spending, a trend that began in Q4 2023. While business (B2B) spending increased 3.6% in the second quarter – higher than Q1 growth of 2.8% – it still was significantly lower than the 5.6% consumer spending growth in nominal terms. On an annualized basis in real terms, business spending expanded only 1%, but consumer spending grew 2.7%, which is nearly 30% higher than in the previous quarter.

In nominal terms, the BEA’s GO advanced 4.5% to exceed $50 trillion for the first time. This growth rate exceeds historical averages, which generally indicates a healthy economy a hints at a potential growth ahead. However, the GO growth lagging behind the GDP growth of 5.6% in Q2 and the lackluster performance of the adjusted GO, indicate that outlook for near-term economic growth is uncertain as we head towards the end of 2024.

Real-term business spending (B2B) growth was relatively flat for the third consecutive quarter. This is a continuing indication that the business sector – which is substantially larger than the retail sector and generally has a better view of the direction of the economy than the consumers – is still cautious about the near future, and that the economy is far from ready for a brisk expansion. While Q2 GDP paints a rosy picture on the surface, an economic slowdown is not out of the question as we close 2024 and transition into 2025.

In addition to lackluster business spending, economic outlook hinges on several additional factors. Domestically, concerns about the outcome of the 2024 presidential election, expectations of Federal Reserve’s actions regarding interest rates that might exacerbate inflation loom over the economy. Internationally, continued impact of the war in Ukraine, economic conditions in Europe and Asia, as well as continued competition with China for global economic and military supremacy are just some of the issues that will impact economic future in the near term.

The Federal Reserve cut the interest rate 50 basis points at its meeting this month. If we exclude emergency rates cuts during the Covid pandemic in 2020, the last time the Fed cut the federal funds rate 50 basis points or more was during the global financial crisis of 2008. With the economy showing no clear signs of rapid growth, the Fed indicated that it might cut the interest rates another 50 basis points over its two remaining meetings in 2024. The slow growth of the Adjusted GO confirms the Fed’s worries about the US economy and its reasoning to cut the interest rates.

Interest rate cuts demonstrate the Fed’s belief that business borrowing is bellow expected levels and that economic growth needs support from easier access to money. While easy money policies do help economic expansion in the short term, those policies inevitably result in higher inflation over the longer term.   

Unlike consumption, which maintains a steady uptrend over the long term, business spending is significantly more volatile and more sensitive to economic fluctuations. Therefore, the tepid business spending growth over the past several quarters, could indicate a mild recession predicted by Adj. GO trailing GDP growth.

Gross Output

GO as a Leading Indicator

In our model, GO, which includes the value of the supply chain, is a leading indicator of where the economy is headed in the year. When GO grows slower than GDP, it suggests economic decline over the next few quarters, and vice versa. Currently, the BEA’s real GO’s second quarter real growth rate of 1.8% is lower than the annualized GDP growth rate of 3.0%, which is usually a sign of an upcoming economic contraction. This indication is further emphasized by the real Adjusted Gross Output (GO*) growth rate of just 1.2% lagging behind both GDP and GO growth, which can mean a stagnating economy.

Gross Output

After three quarters of mixed signals regarding the direction of the economy in the near term, economic data for the second quarter did not offer any more clarity regarding the likely direction of the economy in late 2024 or early 2025. The third-quarter 2024 GO data is scheduled to be released in late December, which will be too late for forecasting economic direction in 2024, but might help in signaling the economy’s path in early 2025.

In nominal terms, second-quarter 2024 GDP expanded 5.6% to exceed $29 trillion for the first time. The BEA’s GO grew 4.5% to cross above the $50 trillion mark – another first. The Adjusted GO – which includes the gross wholesale and gross retail figures (included only as net figures in the GO reported by the BEA) – advanced 3.9% in nominal terms at the end of the second quarter 2024 and is now just shy of $61 trillion. The difference between net and gross figures amounts to nearly $11 trillion, which is missing from the government’s official GO figure, but we include it in our Adjusted GO measure.

Our GO model has proven reliably accurate in projecting the direction of GDP under normal economic circumstances.

The Importance of GO

Most economists are still unaware of the value of GO and use only GDP when gauging economic outlook. However, gross output (GO) should be viewed as the top line in national income accounting, and GDP is the bottom line. Both metrics are essential to understanding where the economy is headed.

As Dale Jorgenson, Steve Landefeld, and William Nordhaus conclude in their book, A New Architecture for the U. S. National Accounts, “Gross output [GO] is the natural measure of the production sector, while net output [GDP] is appropriate as a measure of welfare. Both are required in a complete system of accounts.”

As Steve Forbes has suggested, “GDP is the X-ray of the economy; GO is the CAT-scan.” 

Business – Not Consumers – Drives the Economy

Another benefit of GO is that it dispels the myth that consumer spending drives the economy.  Contrary to views of many academic economists and wide-spread media reports, consumer spending does not represent two-thirds of total economic activity. Using GO as a better and a more accurate measure of total spending in the economy, the business sector (B2B spending) is almost twice the size of consumer spending. Consumer spending is the effect, not the cause, of prosperity (Say’s law).


Gross Output

Therefore, our business-to-business (B2B) index is very useful for assessing the underlying health of the overall economy and its potential to bounce back after economic declines. The B2B Index measures all the business spending in the supply chain and new private capital investment. After a 3.0% expansion in the previous quarter, nominal B2B spending grew again in Q2 2024. The 3.6% second-quarter growth pushed business spending to $34.5 trillion. At the same time, consumer spending expanded 5.4% to $19.7 trillion. However, the higher-than-normal inflation reduced consumer spending growth to just 2.7% in real terms. Inflation impact was even more evident in business spending as the 3.6% growth in nominal terms became a growth of just 1.0% in real terms. This low growth in real terms only reversed the contraction form the two previous periods and brought the real B2B spending back to Q3 2023 level. 

“B2B spending is in fact a pretty good indicator of where the economy is headed, since it is more responsive to the boom-bust economic cycle than consumer spending,” states Mark Skousen, editor of Forecasts & Strategies and the Doti-Spogli Chair of Free Enterprise at Chapman University.

While GDP includes only a small portion of investment spending, GO accounts for significantly more of the business investment outlays, which tend to indicate economic direction over extended periods. As David Ranson, chief economist for the private forecasting firm HCWE & Co., states, “Movements in gross output serve as a leading indicator of movements in GDP.”

The federal government will release the advance estimate for third-quarter 2024 GDP on October 30, 2024. The full release of Q2 Gross Output data, as well as the third estimate of GDP are scheduled for December 19, 2024.

Important Note:  We are hopeful that in the near future, the BEA will release GO at the same time as the first estimate of GDP for the quarter, not the third estimate. We also recommend that GO be elevated in the BEA’s press releases and website as the “top line” in national income accounting, since GO data often tells a very different story than GDP data.

Report on Various Sectors of the Economy

Three of the major economic sectors experienced a pullback again in Q2 2024 as they did in the previous period. Moreover these three sectors are in the very early stages of production, which generally are better early indicators of economic direction than later stages of production.

After declining 1.2% in Q1, the Agriculture sector contracted an additional 9.1% in the second quarter. This marks the third consecutive quarter of contraction in real terms for the sector. The Mining sector reversed a contraction from Q1 (-6.1%) and expanded slightly at 1.7% in the second quarter. However, the Utilities segment – which experienced a slight growth of 1% in Q1 after a 5.7% decline in the last period of 2023 – delivered a largest decline of any sector this period and shrunk more than 25% in Q2 2024.

While these three sectors account for only 3.9% of the overall economy, they are all early-stage sectors, which can signal how the later stages and the overall economy might shift over the subsequent few periods.

One bright point in the earlier stages of production was the Construction sector (4.4% share of the economy), which followed up a healthy 7.3% real-term growth in the first quarter of 2024 with an even stronger expansion of 15% in the second quarter.

However, the main reason for concerns about economic growth is the Manufacturing sector. After expanding less than 1% in the last quarter of 2023, and then delivering no growth in the first quarter of 2024, the second-largest sector with a 14.5% share of the overall economy, contracted nearly 2% in Q2 2024. The contraction affected both Durable goods (-1.1%) and Nondurable goods (-2.6%). The Wholesale sector expanded 3.6% and the Retail sector grew 2.6%.

The largest segment that accounts for nearly a fifth of the overall economy – Finance, insurance, real estate, rental, and leasing – inked only a small expansion of just 0.5% in real terms. While Real estate and rental and leasing subsector expanded 4.4%, the Finance and insurance subsector contracted 5.1%.

Three late-stage sectors – Professional and business services; Educational services, health care, and social assistance; and Arts, entertainment, recreation, accommodation, and food services, which account combined for more than a 23% of the overall economy – expanded 6.0% and 9.8%, and 8.7% respectively. 

Prior to Q2 2024, the government spending growth rate declined for three consecutive quarters. However, the growth rate decline come to an end this period. Total overall government spending in real terms expanded 2.7% in the second quarter. After shrinking for two consecutive periods, Federal government spending expanded 1.3% in Q2 2024. However, the bigger concern is the 3.1% spending expansion of State and local governments, which account for 70% of total government spending.

Gross output (GO) and GDP are complementary statistics in national income accounting. GO is an attempt to measure the “make” economy; i.e., total economic activity at all stages of production, similar to the “top line” (revenues/sales) of a financial accounting statement. In April 2014, the BEA began to measure GO on a quarterly basis along with GDP.

Gross domestic product (GDP) is an attempt to measure the “use” economy, i.e., the value of finished goods and services ready to be used by consumers, business and government. GDP is not quite the same as the “bottom line” (profit, or net income) of an accounting statement, but rather the “value added” or the value of final use.

GO tends to be more sensitive to the business cycle, and more volatile, than GDP.

About GO and B2B Index

Skousen champions Gross Output as a more comprehensive measure of economic activity. “GDP leaves out the supply chain and business to business transactions in the production of intermediate inputs,” he notes. “That’s a big part of the economy, bigger than GDP itself. GO includes B2B activity that is vital to the production process. No one should ignore what is going on in the supply chain of the economy.”

Skousen first introduced Gross Output as a macroeconomic tool in his work The Structure of Production (New York University Press, 1990). A new third edition was published in late 2015 and is now available on Amazon.

Click here: Structure of Production on Amazon

The BEA’s decision in 2014 to publish GO on a quarterly basis in its “GDP by Industry” data is a major achievement in national income accounting. GO is the first output statistic to be published on a quarterly basis since GDP was invented in the 1940s.

The BEA now defines GDP in terms of GO. GDP is defined as “the value of the goods and services produced by the nation’s economy [GO] less the value of the goods and services used up in production (Intermediate Inputs or II].” See definitions at https://www.bea.gov/newsreleases/industry/gdpindustry/gdpindnewsrelease.htm

With GO and GDP being produced on a timely basis, the federal government now offers a complete system of accounts. As Dale Jorgenson, Steve Landefeld, and William Nordhaus conclude in their book, A New Architecture for the U. S. National Accounts, “Gross output [GO] is the natural measure of the production sector, while net output [GDP] is appropriate as a measure of welfare. Both are required in a complete system of accounts.”

Skousen adds, “Gross Output and GDP are complementary aspects of the economy, but GO does a better job of measuring total economic activity and the business cycle, and demonstrates that business spending is more significant than consumer spending,” he says. “By using GO data, we see that consumer spending is actually only about a third of economic activity, not two-thirds that is often reported by the media. As the chart above demonstrates, business spending is in fact almost twice the size of consumer spending in the US economy.”

For More Information

For a complete analysis of GO, go to https://www.grossoutput.com/gross-output/

The GO data released by the BEA can be found at www.bea.gov under “Quarterly GDP by Industry.” Click on interactive tables “GDP by Industry” and go to “Gross Output by Industry.” Or go to this link directly: https://apps.bea.gov/iTable/?reqid=150&step=2&isuri=1&categories=gdpxind

Mark Skousen, “Slow GO May Mean a Recession Soon” Wall Street Journal, April 4, 2024: https://www.wsj.com/articles/slow-go-may-mean-a-recession-soon-us-economy-real-gross-output-65c4f1fd?mod=commentary_article_pos3

Peter Coy, “What GDP’s Cousin Can Tell Us about the Economy,” August 7, 2023, New York Times:  https://www.nytimes.com/2023/08/07/opinion/gdp-recession-gross-output.html?searchResultPosition=1

Mark Skousen, “Recession Fears May Not Pass GO: GDP is Slumping, but There’s a Better Way to Gauge the Economy.” Wall Street Journal, August 11, 2022: Recession Fears May Not Pass GO – WSJ 

If you are not a WSJ subscriber, you can read a copy of the article on: https://www.grossoutput.com/2022/09/12/recession-fears-may-not-pass-go/

Emma Rothschild, “Where is Capital?” in Capitalism: A Journal of History and Economics 2:2 (Summer 2021), pp. 291-371.  https://muse.jhu.edu/article/798746   “Essentially an attempt to apply ideas about gross output to the economic history of the industrial revolution.”  

GO-Day podcast discussion panel hosted Mark Skousen that included Steve Forbes, Sean Flynn, Steve Hanke, and David Ranson, September 30, 2020: https://chapman.zoom.us/rec/share/KJ17YjuR_6zthmgOA5fNprv2e65F-jICOsf430bJvnu8qWzdPYPfTohPC48qRLe9.Q8rmnlXynnTN74Tv?startTime=1601488807000

Steve Forbes: What’s Ahead podcast. In this podcast, Steve Forbes discusses Gross Output with Mark Skousen on September 9, 2019; he compared GDP to an X-ray of the economy, and GO to a CAT-scan: :  https://www.forbes.com/sites/steveforbes/2019/09/09/were-using-the-wrong-measure-gdp-to-gauge-the-economys-real-health-mark-skousen/#35ff3d9a52fa


For more information on Gross Output (GO), the Skousen B2B Index, and their relationship to GDP, see the following:

Mark Skousen, “If GDP Lags, Watch the Economy Grow,” Wall Street Journal, April 24, 2018:  https://www.grossoutput.com/2018/04/26/away-go-economy-growing-faster-expected/

Mark Skousen, “At Last, a Better Way to Economic Measure” lead editorial, Wall Street Journal, April 23, 2014: http://on.wsj.com/PsdoLM

Steve Forbes, Forbes Magazine (April 14, 2014): “New, Revolutionary Way To Measure The Economy Is Coming — Believe Me, This Is A Big Deal”: http://www.forbes.com/sites/steveforbes/2014/03/26/this-may-save-the-economoy-from-keynesians-and-spend-happy-pols/

Mark Skousen, Forbes Magazine (December 16, 2013): “Beyond GDP: Get Ready For A New Way To Measure The Economy”: http://www.forbes.com/sites/realspin/2013/11/29/beyond-gdp-get-ready-for-a-new-way-to-measure-the-economy/

Steve Hanke, Globe Asia (July 2014): “GO: J. M. Keynes Versus J.-B. Say,” http://www.cato.org/publications/commentary/go-jm-keynes-versus-j-b-say

David Ranson, “Output growth data that the economy generates months earlier than GDP,” Economy Watch, July 24, 2017. HCWE & Co. http://www.hcwe.com/guest/EW-0717.pdf

Mark Skousen, “Linking Austrian Economics to Keynesian Economics,” Journal of Private Enterprise, Winter, 2015: http://journal.apee.org/index.php?title=Parte7_Journal_of_Private_Enterprise_vol_30_no_4.pdf

To interview Dr. Mark Skousen on this press release, contact him at [email protected], or Ned Piplovic, Media Relations at [email protected].

# # #

________________________________________

[1] The BEA currently uses a limited measure of total sales of goods and services in the production process. Once products are fabricated and packaged at the manufacturing stage, the BEA’s GO only adds “net” sales at the wholesale and retail level. Its official GO for the second quarter of 2024 is slightly over $50 trillion. By including gross sales at the wholesale and retail level, the Adjusted GO (GO*) expands to more nearly $61 trillion in Q2 2024. Thus, the BEA omits nearly $11 trillion in business-to-business (B2B) transactions in its GO statistics. We include them as a legitimate economic activity that should be accounted for in GO, which we call Adjusted GO. See the new introduction to Mark Skousen, The Structure of Production, 3rd ed. (New York University Press, 2015), pp. xv-xvi.


Filed Under: Articles, Featured Story, Main

  • 1
  • 2
  • 3
  • …
  • 7
  • Next Page »

Connect with Mark Skousen

  • Email
  • Facebook
  • LinkedIn
  • Twitter

Mark Skousen’s Top Ten

Top Ten

Recent Posts

Gross Output

Good Sign: Business Spending is Finally Making a Comeback!

“By integrating the vital role of the supply chain into national income … [Read More...]

Gross Output

Fourth Quarter GO Confirms Deepening Stagflation into 2026

“By integrating the vital role of the supply chain into national income … [Read More...]

My Interview with Nobel Prize Recipient Vernon Smith

Vernon Smith Interview Chapman University March 9, 2026 Mark Skousen: … [Read More...]

Big Announcement: I’m Starting a New Career at the Oxford Club, and You Are Invited to Join Me!

“Life, like a dramatic piece, should finish handsomely.  I am very desirous of … [Read More...]

Gross Output

Trump Trade War Hits Business: Economy Slows to a Crawl

“By integrating the vital role of the supply chain into national income … [Read More...]

Gross Output

Consumers Are Cautious at the Start Of 2025, but Businesses Show Confidence in Near-Term Growth.

Washington, DC (Thursday, June 26, 2025): Today the federal government’s Bureau … [Read More...]

FreedomFest

FreedomFest 2025 – Day Two

Dear FreedomFest Attendee, What an amazing start to FreedomFest yesterday! As … [Read More...]

Gross Output

Business Spending Flat to Close 2024, Economic Outlook Uncertain for 2025

  “By integrating the vital role of the supply chain into national income … [Read More...]

Gross Output

Business Spending Rebounds, Recession Avoided

  “By integrating the vital role of the supply chain into national income … [Read More...]

Birthday 2024

Dear friends, Thanks for all the birthday cards and emails. Today's … [Read More...]

Gross Output

Slowing Gross Output Confirms Fed’s Need to Cut Rates

  “By integrating the vital role of the supply chain into national income … [Read More...]

Reagan

“Reagan” movie – any good?

Dear friends, Jo Ann and I just saw the "Reagan" film. Despite the negative … [Read More...]

Gross Output

Low Business (B2B) Spending Confirms Stagflation in 2024

  “By integrating the vital role of the supply chain into national income … [Read More...]

My Schedule at FreedomFest 2024

Dear freedom lovers from around the world, Roberto Salinas says, “This is the … [Read More...]

Ivy League Bound

Teaching at Columbia University with the Help of William F. Buckley, Jr. and … [Read More...]

Milton Friedman, Individualist

Remarks on Jennifer Burn’s book, “Milton Friedman, the Last Conservative” (New … [Read More...]

Gross Output

This just out on WSJ.com – and will make the printed copy on April 5, 2024

The Wall Street Journal has accepted all four of my op eds on GO over the … [Read More...]

Gross Output

Business Stagnates While GDP Advances 3.4% – Downturn Still Looming for 2024

  “By integrating the vital role of the supply chain into national income … [Read More...]

Tyler Cowen’s GOAT (Barely) Misses the BOAT

Review of Tyler Cowen’s GOAT: Who is the greatest economist of all time and why … [Read More...]

There Were Giants in the Land

“Bring Back Skousen!” Announcing Our Latest Book

By Mark Skousen “Cleon Skousen was truly a giant. I encourage everyone to … [Read More...]

FreedomFest 2023 Memphis

My Schedule at FreedomFest Memphis 2023, Renasant Convention Center.

Dear freedom lovers, I’m excited about this year’s big show in Memphis.  … [Read More...]

ChatGPT

GPT4 Gets it Right about Mark Skousen!

Tyler Cowen, GMU professor and host of the popular website … [Read More...]

Robert E. Lucas Jr.

Robert Lucas, Jr., Nobel Prize Winner, R.I.P.

Dear friends,   Another free-market economist has passed away.  Robert Lucas, … [Read More...]

Stanley Engerman

Stanley Engerman, Co-Author of “Time on the Cross,” R. I. P.

Stanley Engerman, economic historian at the University of Rochester, died on May … [Read More...]

FreedomFest 2019: Mark Skousen & Jo Ann Skousen – Investing for Two: How Couples Can Successfully Manage Their Finances Breakfast

… [Read More...]

Three Nobel Prize Winners Endorse New Macro Statistic

by Mark Skousen I now have three Nobel prize winners who are encouraging my … [Read More...]

Gross Output

Supply Chain Business Still Growing: Recession Fears May Not Pass GO

Washington, DC (Thursday, September 29, 2022): Today, the federal government … [Read More...]

Are economists the slowest learners?

Dear friends of freedom, Peter Drucker once said, "Economists are the slowest … [Read More...]

FreedomFest Agenda – Here’s a preview:

Dear friends of FreedomFest, The excitement is building for our July 13-16 … [Read More...]

Making of Modern Economics

Richard Rahn Reviews “The Making of Modern Economics” by Mark Skousen

Richard W. Rahn — economist, syndicated columnist and entrepreneur — reviewed … [Read More...]

Making of Modern Economics

“The Making of Modern Economics” – The book the New Socialists fear the most

Good news! The brand-new fourth edition of “The Making of Modern Economics” has … [Read More...]

Franklin

Why Ben Franklin Matters

Today is the 316th anniversary of the birth of founding father extraordinaire … [Read More...]

Economy

Economy Slows, But the Outlook is Still Positive

Washington, DC (Wednesday, December 22, 2021): Today, the federal government … [Read More...]

Samuelson vs Friedman, Match of the Century

By: Mark Skousen First published in the March 1999 issue of Liberty … [Read More...]

Gross Output

Despite Higher Inflation, the U.S. Economy Continues to Boom: Gross Output (GO) Hits $50 Trillion!

Washington, DC (Thursday, September 30, 2021): For the first time in history, … [Read More...]

Are we Rome?

Are We Rome?

By Mark Skousen Talk delivered on Saturday, September 11, 2021, Kimber … [Read More...]

Economy

While Inflation Threatens, the U.S. Economy is Firing on All Cylinders

  Washington, DC (Thursday, June 24, 2021): On June 24, 2021, the federal Bureau … [Read More...]

FreedomFest

Fun Things to Do at FreedomFest This July

We already have more than 2,000 registered attendees for FreedomFest next month. … [Read More...]

Walter Lippmann

Where’s Walter Lippmann when we need him?

Columnist and author Walter Lippmann (1889-1974) was considered the most … [Read More...]

Gross Output

Gross Output (GO) Growth Outpaces GDP Again to Suggest Robust Recovery

Washington, DC (Thursday, March 25, 2021): On March 25, 2021, the federal Bureau … [Read More...]

Gross Output

Business-to-Business (B2B) Spending Grows Faster Than GDP!

Washington, DC (Tuesday, December 22, 2020): On December 22, 2020, the federal … [Read More...]

Maxims

Ideal Holiday Gift! New 10th Anniversary Release of “The Maxims of Wall Street”

Dear friends, A hundred years ago, in 1920, the great author and poet Rudyard … [Read More...]

Ezra Taft Benson

Ezra Taft Benson’s Remarks at FEE Headquarters in New York, May 1977

In 2001-02, I served as president of the Foundation for Economic Education … [Read More...]

Ezra Taft Benson in Russia

Elder Ezra Taft Benson Speaks in Communist Russia

    “It was the most heart-rending and most inspiring scene … [Read More...]

lessons

10 LESSONS FOR 10-10-2020

This article was originally published on the FreedomFest Forum on October 10, … [Read More...]

GO-Day Celebration

Dear friends, Good news!  For the first time, the federal government (BEA) … [Read More...]

Gross Output

Macroeconomics on the GO: How Wall Street Economic Analysts Use Gross Output (GO)

Here are two examples of how private economic research firms are using gross … [Read More...]

Gross Output

Despite First Decline in More Than a Decade for Q1, Gross Output (GO) Might Still Offer Hope for a Robust Recovery in Late 2020

Washington, DC (Tuesday, July 7, 2020):  On July 6, 2020, the federal Bureau of … [Read More...]

FreedomFest

My Schedule at FreedomFest 2020

by Mark Skousen Editor, Forecasts & Strategies   Dear … [Read More...]

Forecasts & Strategies

40 Year of Forecasts & Strategies

Dear friends, My publisher, Salem Eagle, has just posted my special 40th … [Read More...]

GO

U.S. Economy on the GO: Total Spending Accelerates

Washington, DC (Thursday, January 9, 2020):  On January 9, 2020, the Bureau of … [Read More...]

MODERN MONETARY THEORY

THERE’S MUCH RUIN IN A NATION: MODERN MONETARY THEORY

By Mark Skousen Chapman University [email protected] “Today, as in the … [Read More...]

Forbes

Steve Forbes on the GO: I Make the Forbes 400 Richest Issue!

I’m mentioned on page 22 for my gross output (GO) model. (Sorry, I may be worth … [Read More...]

MY INTELLECTUAL ANCESTORS

BY MARK SKOUSEN Presidential Fellow, Chapman University "If I have seen a … [Read More...]

Trade

Trade War Threatens Recession

Washington, DC (Monday, July 29, 2019): On July 19, 2019, the federal … [Read More...]

FreedomFest

MY SCHEDULE AT FREEDOMFEST 2019

by Mark Skousen Editor, Forecasts & Strategies   Dear FreedomFest … [Read More...]

Austrian

AUSTRIAN VS. CHICAGO ECONOMISTS: RESPONSE TO THE 2008 FINANCIAL CRISIS

By Mark Skousen Updated in 2019  “Blessed paper credit! Last and best … [Read More...]

Gross Output

GO Confirms a Slow-Growth Economy as We Enter 2019

Washington, DC (Friday, April 19, 2019): Today the federal government released … [Read More...]

Gross Output

The US Economy is NOT Slowing Down. Business Spending Soars!

By Mark Skousen Editor, Forecasts & Strategies Washington, DC (Thursday, … [Read More...]

Making of Modern Economics

The Economist Publishes New Ad for “Making of Modern Economics”

The November 24th issue of The Economist, page 73, is running a new full-page … [Read More...]

Gross Output

Gross Output Indicates Continued Boom in the U.S. Economy as Business Spending Expands Rapidly in Q2

Washington, DC (Thursday, November 1, 2018):  Gross output (GO), the top line of … [Read More...]

Adam Smith

ADAM SMITH AND THE MAKING OF MODERN ECONOMICS

By Mark Skousen Presidential Fellow, Chapman … [Read More...]

Gross output

US Economy Continues to Expand, but Business Spending Slows Temporarily

Washington, DC (Friday, July 20, 2018):  Gross output (GO), the top line of … [Read More...]

Steve Forbes

Full Remarks by Steve Forbes On the Presentation of a Triple Crown in Economics to Mark Skousen

The following are Mr. Forbes remarks following Skousen’s session on “Adam Smith, … [Read More...]

Steve Forbes

STEVE FORBES AWARDS MARK SKOUSEN A TRIPLE CROWN IN ECONOMICS

For Immediate Release July 18, 2018 Washington, DC:  Steve Forbes, chairman … [Read More...]

Mark Skousen’s article on Revista Procesos de Mercado (Review of Market Processes)

Revista Procesos de Mercado (Review of Market Processes) has just published Mark … [Read More...]

If GDP Lags, Watch the Economy GO

‘Gross output’ reflects the full value of the supply chain, and it portends much … [Read More...]

Away We GO: Business Spending Accelerates in 4th quarter 2017

Washington, DC (Thursday, April 19, 2018) Gross output (GO), the top line of … [Read More...]

GO

GO Slow: New Leading Indicator Predicted Slowdown in GDP

by Mark Skousen Presidential Fellow, Chapman University Editor, Forecasts … [Read More...]

gross output

THIRD QUARTER GROSS OUTPUT AND B2B SPENDING GAIN MOMENTUM

Washington, DC (Friday, January 19, 2018): Gross output (GO), the top line of … [Read More...]

2ND QUARTER GROSS OUTPUT SHOWS SURPRISE SLOWDOWN IN ECONOMY

Washington, DC (Thursday, November 2, 2017): Gross output (GO), the top line of … [Read More...]

Economic Logic

ANNOUNCING A NEW EDITION BREAKTHROUGH COURSE IN FREE-MARKET CAPITALISM

“Mark Skousen is America’s leading economic author because he roots his luminous … [Read More...]

Gross Output

RAPID GROWTH IN 1ST QUARTER GO: ECONOMY IS NOT SLOWING DOWN

By: MARK SKOUSEN Washington, DC (Wednesday, July 26, 2017): Gross output … [Read More...]

GROSS OUTPUT AND B2B INDEX ADVANCE SHARPLY AFTER ELECTION

Washington, DC (Friday, April 21, 2017): Gross output (GO), the top line of … [Read More...]

SECOND QUARTER GROSS OUTPUT AND B2B INDEX INCREASE, STILL NO SIGNIFICANT GROWTH OF THE U.S. ECONOMY.

By Mark Skousen Washington, DC (Thursday, November 3, 2016):  Gross output, … [Read More...]

FIRST QUARTER GROSS OUTPUT AND B2B INDEX POINT TO NEGLIGIBLE GROWTH OF THE U.S. ECONOMY

Washington, DC (Thursday, July 21, 2016):  U. S. economic activity is still … [Read More...]

HOW BEN FRANKLIN SAVED THE POST OFFICE AND HELPED UNIFY AMERICA

By Mark Skousen Special to the Franklin Prosperity Report July 4, … [Read More...]

FreedomFest Fun Activities

In addition to all the great debates, presentation and hundreds of vendors in … [Read More...]

Big news: the Bureau of Economic Analysis (BEA) has changed its definition of GDP that starts with Gross Output.

This is a significant breakthrough, which I have encouraged them to do for some … [Read More...]

FOURTH QUARTER GROSS OUTPUT AND B2B INDEX POINT TO BUSINESS RECESSION

By Mark Skousen April 21, 2016 Washington, DC (Thursday, April 21, 2016):  … [Read More...]

CATO INSTITUTE POLICY FORUM: “GO Beyond GDP: What Really Drives the Economy?”

We hear constantly that consumer spending is 70% of GDP and that consumer … [Read More...]

ANNOUNCING THE NEW THIRD EDITION OF “THE MAKING OF MODERN ECONOMICS” BY MARK SKOUSEN

March 9, 2016: Today marks the 240th anniversary of the publication of “The … [Read More...]

Announcing the New Third Edition of “The Structure of Production”

Federal Government Introduces a New Macro Statistic: A Triumph in Supply-side … [Read More...]

My Friendly Fights with Dr. Friedman

The Rational, The Relentless - Liberty Magazine - September 2007 by Mark … [Read More...]

My Schedule at FreedomFest 2026 – Exciting Topics at this Year’s FreedomFest

Dear FreedomFesters, Greetings and happy July 4th!  To get you in the mood … [Read More...]

The Making of Modern Economics

Recent Comments

  • Ned Piplovic on Big Announcement: I’m Starting a New Career at the Oxford Club, and You Are Invited to Join Me!
  • Richard Skalos on Big Announcement: I’m Starting a New Career at the Oxford Club, and You Are Invited to Join Me!
  • Ned Piplovic on Big Announcement: I’m Starting a New Career at the Oxford Club, and You Are Invited to Join Me!
  • Robert Greenlee 303-956-0597 on Big Announcement: I’m Starting a New Career at the Oxford Club, and You Are Invited to Join Me!
  • Ned Piplovic on Consumers Are Cautious at the Start Of 2025, but Businesses Show Confidence in Near-Term Growth.

Contact Mark Skousen

Personal Email

Forecasts & Strategies Email

FreedomFest Email

Social Media:
Facebook
LinkedIn
Twitter

Websites:
mskousen.com
markskousen.com
freedomfest.com

Mark Skousen Newsletters

 Mark Skousen Investment Newsletters

Since 1980, Skousen has been editor in chief of Forecasts & Strategies, a popular award-winning investment newsletter. He also is editor of three trading services, Skousen Private Equity Trader; Skousen High-Income Alert and Fast Money Alert.

Jo Ann Skousen’s Odds & Trends

Jo Ann Skousen

Movie reviews, theater reviews, and commentaries by Jo Ann Skousen, author, editor, professor and Mark's wife of 41 years. She is the Festival Director for the Anthem Libertarian Film Festival and the entertainment editor for Liberty Magazine.

Mark Skousen’s Investor’s CAFE

Mark Skousen Investors CAFE

Skousen Investor CAFÉ is a weekly electronic newsletter written by Dr. Mark Skousen. Mark offers commentary on the markets, the economy, politics and other topics of interest and what they mean to individual investors. Sign up for FREE here.

FreedomFest Conference


FreedomFest is an annual festival in Las Vegas where free minds meet to celebrate “great books, great ideas, and great thinkers” in an open-minded society. It is independent, non-partisan, and not affiliated with any organization or think tank.

Anthem Film Festival

Anthem Libertarian Film Festival

Anthem is the only film festival in the country devoted to promoting libertarian ideals. Anthem shows films and documentaries that celebrate self-reliance, innovation, commerce, individual rights, and the power of persuasion over force. We are looking for the year's best films about personal and civil liberty.

Copyright © 2026 · Mark Skousen · Log in

✖

Cancel reply

Cancel